Our Analyses

When Life Gives You (Lulu)lemons, Buy LULU Shares 

By Saamia Khan

Back in 1998, Lululemon Athletica founder and former CEO Chip Wilson attended a yoga class where inspiration struck. Coining the term “yoga pants,” Wilson created a company based on women’s yet-to-be-discovered need for a comfy pants. Fast forward 20 years, yoga pants and athleisure as a whole have skyrocketed in popularity, reflecting the changing American fashion landscape. In 2014, teens preferred elastic-waistband pants, overtaking the ever-popular pair of jeans. Athleisure as a whole has grown to a massive $167B industry, and will take up an even larger portion of clothing sales as the shift in preferences continues. 

Since its founding in 1998, Lululemon has established a total of 460 stores, mainly in the U.S. and Canada. It has evolved from selling just yoga pants to becoming an icon for all types of athletic wear, outerwear, and shoes (partnering with Athletic Propulsion Lab) for women, men, and girls. Recently, they launched a new line (“Lab”), a high-end streetwear separate brand with a price range of $80-$500 per item. With its $100 leggings feeding into nearly $3.3B of revenue in 2018, LULU stock has been gaining significant traction in the investment world, especially over the past year. With an EPS of $4.51, the stock’s recent high of $229.65 on November 29th is a more than 100% increase since its 52 week low of $110.71. 

While recognizing it does not trade cheaply, we believe Lulu is undervalued as the company sets itself apart with its tremendous yet realistic growth opportunities. LULU is a buy. 

Three-Pronged Approach for a 5-year plan (“Power of Three”)

Lululemon has three main target areas that feed into its optimistic mid-teens revenue growth numbers: an expansion into the international arena, increasing menswear sales, and doubling online sales. 

1. International Growth: 

Lululemon plans to greatly expand in Europe and Asia by 2024. The Asian market is one that Lululemon has yet to crack, and the next 5 years will be an important pivot to a greater global presence. The company currently operates 29 stores in China, and expects to open an additional 55 by 2024. In Europe, Lululemon has 12 stores and aims to open another 40 in the next 5 years. Overall, the company aims to have a total of 670 stores worldwide by 2024, a significant increase from its current 460.

2. Menswear

Though initially catering only to women, Lululemon expanded its offerings to men in 2015. Since its menswear launch, the company has struggled with the issue of being recognized as a dual-gendered brand. However, in recent quarters, the line has kicked off following the launch of their most popular men’s item, the ABC pant. Menswear sales increased by 28% in Q2 2019. The line is poised to continue its expansion in the coming years, and is set to more than double in sales in the next two years with the help of an ambitious marketing strategy. In the words of COO Stuart Haselden: “It’s growing faster than our women’s business.”

3. Online Sales

Lululemon has projected that direct-to-consumer (DTC) sales will at least double by 2024, a reasonable target given the company’s ability to drive online traffic in recent quarters. Online sales were up nearly 50% in the past year. In terms of profitability, online sales eliminate a plethora of costs between manufacturing and delivery to the consumer, hence allowing for margins of over 40%, compared to ~20% with in-store sales. These increased margins will help power overall company margins and offset costs in other areas. 

—
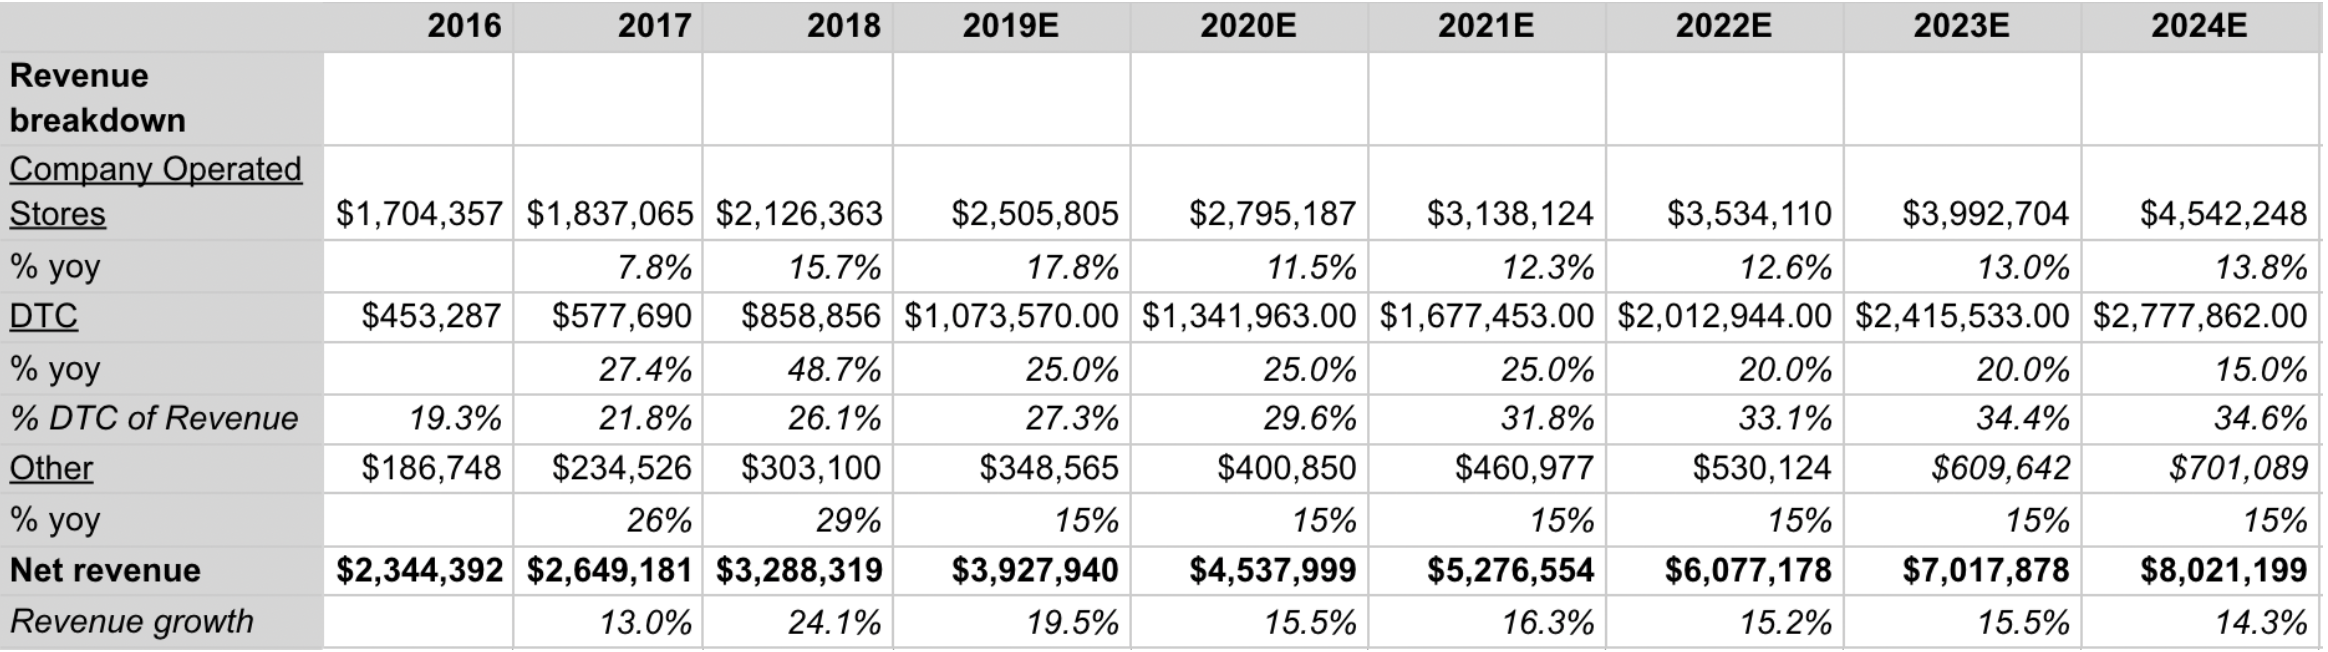
 In considering this three-pronged approach, it is apparent that Lululemon Athletica is exploring new avenues for revenue growth, having only just commenced its worldwide expansion. We assume a consistent revenue stream for each store opened until 2024 based on current figures. We also expect online sales to continue its growth in the double digits and subscription-based revenue growth of 15% per year (Other). Putting the above three revenue avenues together, we predict that Lululemon is poised for consistent revenue growth in the mid-teens through 2024. 
Just a Trend? On Brand Strength and Loyalty.

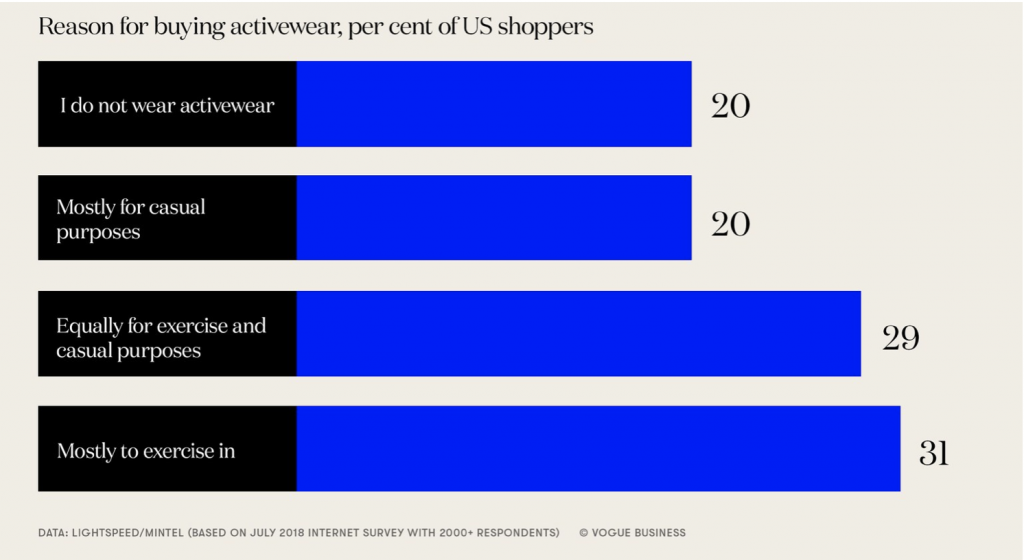
Lululemon’s projected success detailed above is contingent not only on the attraction of its products, but on the general success of the athleisure industry as a whole. There is a general push towards “wellness,” and buying goods that feed into this mindset. In fact, a growing percentage of Americans buy activewear not just for athletic activities, but as everyday wear.
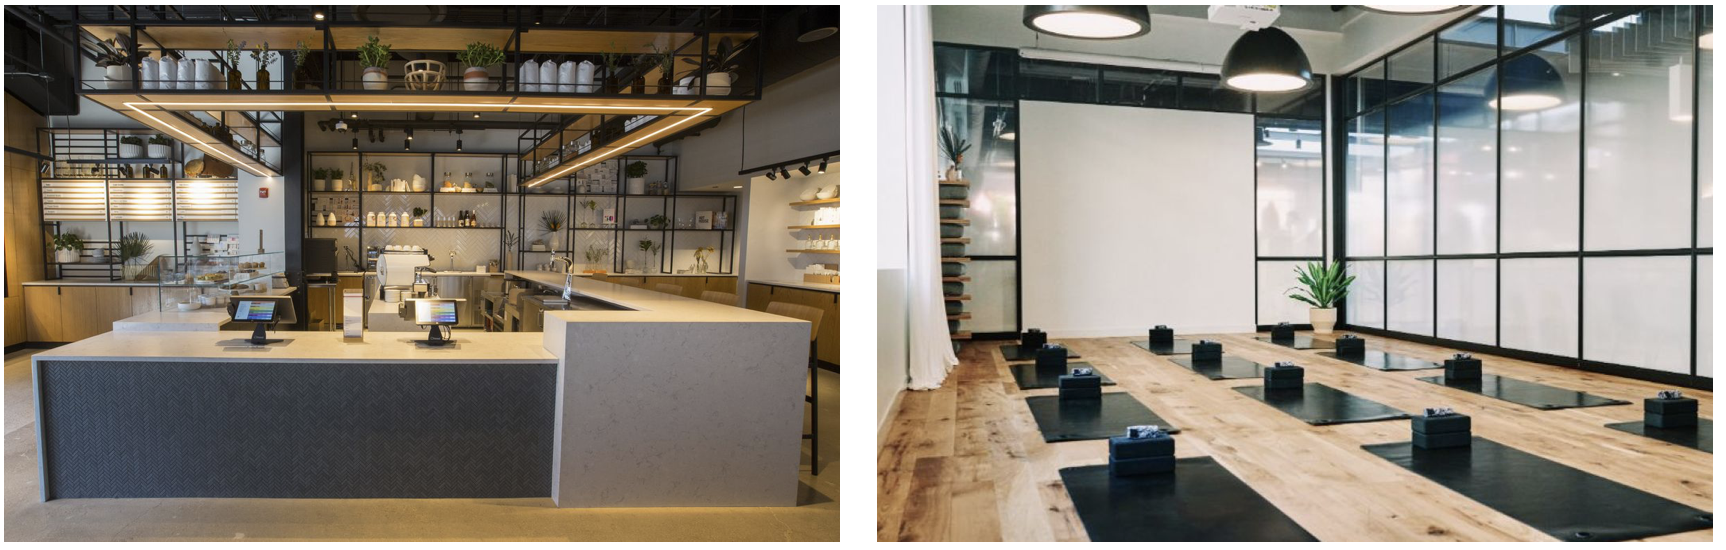
Images from Lululemon’s experiential store in Chicago offering smoothies and yoga classes, reflective of the company’s push to integrate customers into a larger ecosystem.

Moreover, Lululemon has emerged from its position as a mere retailer. It is no longer a brick-and-mortar shop where purchasing athletic gear is the only appeal. First, the Lululemon brand is especially prominent and the name-value brings with it a host of advantages, a feature its customer base is most definitely aware of. The distinct reflective horseshoe logo has become a recognizable symbol of wellness and athleticism. As mentioned above, in addition to in-store and direct-to-consumer sales, a third portion of revenue comes from subscriptions. Lululemon has recently made a large push towards incorporating customers into a greater ecosystem, offering yoga classes and membership to running clubs. Its new paid loyalty program, similar to a program that current Lululemon CEO Calvin McDonald implemented during his tenure as CEO at Sephora, ensures customers return for limited-edition products, free expedited shipping, and other perks. As of Q3 2019, the program has had positive “results [that] have been well above our expectations going in very favorable,” according to McDonald. They have teamed up with SoulCycle to offer custom-made gear, solidifying its name in the high-end athletic space. 
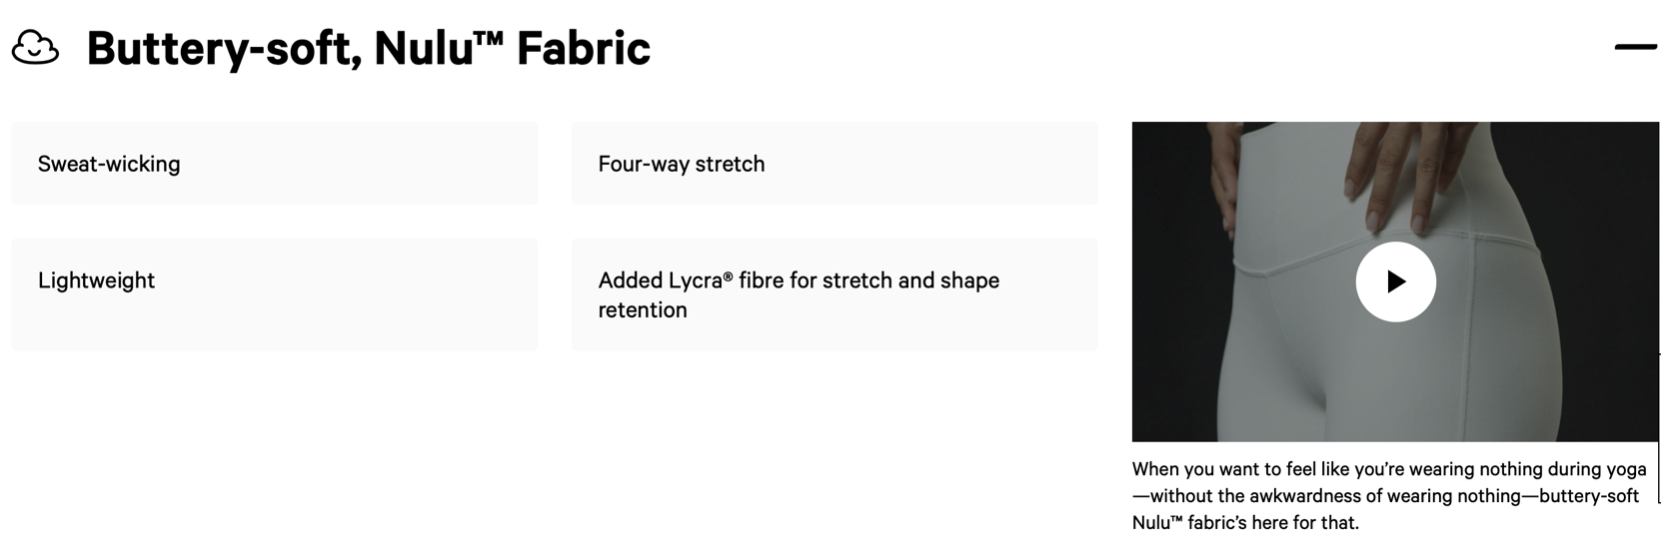
From Lululemon’s website: a look into its differentiating technology

Lululemon also sets itself apart due to its technology. The company’s research and development lab within its headquarters, Whitespace, is made up of around 50 employees that include scientists and physiologists. Lululemon’s quality goods contribute to the company’s strong ability to retain customers while demanding a high price point.

Strong Financials

Lululemon has a great balance sheet, especially for a more than 20-year-old company, the main takeaway being that they have no long-term debt. With continued revenue growth and higher margins, we expect cash flow to sustain and reflect in shareholder’s equity.

Comps
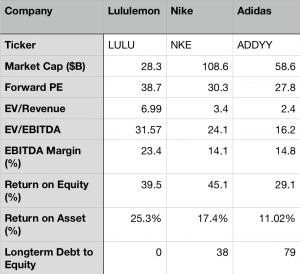
In comparison to its largest competitors, Nike and Adidas, Lululemon certainly seems to be the most overvalued. Despite its high EV/Revenue and EV/Revenue numbers, Lululemon’s small market cap in comparison to Nike and Adidas is indicative of its immense growth opportunities. Moreover, its return on asset figure is higher than competitors, an attractive quality for growth valued company.

Risks: A Discussion

I will address a few potential risks to Lululemon’s revenue growth.
Tory Burch’s luxury athletic wear store, Tory Sport, on Fifth Avenue

A main worry in the athleisure industry is the low barriers to entry and the resulting competition. Seeing Lululemon’s high margins, it is an attractive industry for outsiders. In recent years, Nike and Adidas have greatly expanded their women’s lines in an effort to compete with Lululemon. Many higher-end names such as Tory Burch alongside streetwear brands such as KITH have also waded into the athleisure space. However, as discussed earlier, Lululemon has and continues to integrate customers into a larger Lulu ecosystem, making Lululemon more than just a retailer. At the same time however, changing preferences and trends could potentially have large impacts on Lulu’s profitability. 
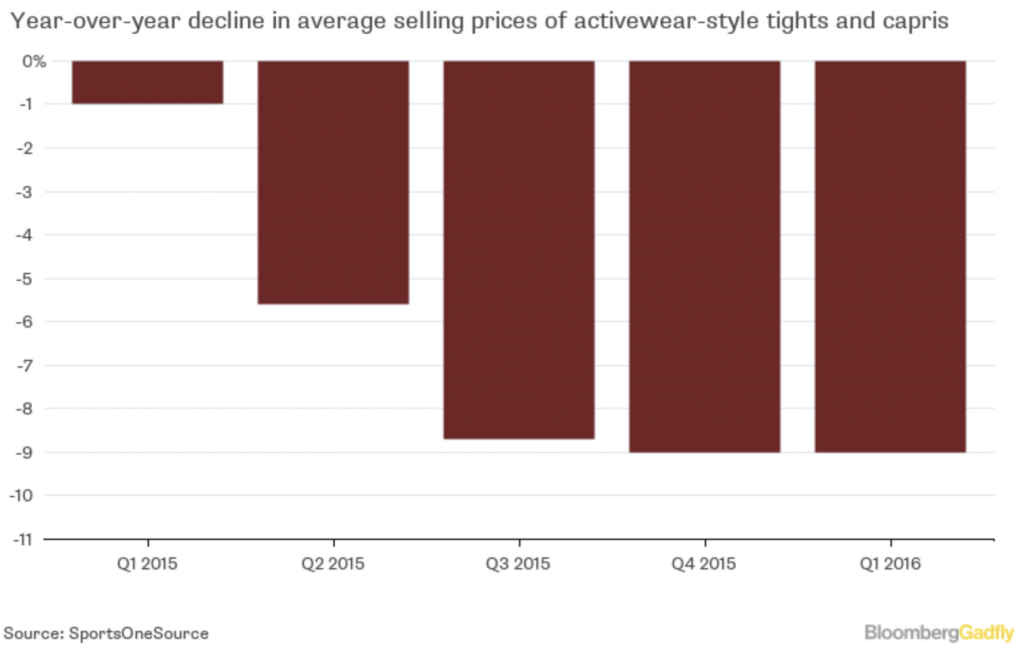
Another concern with low barriers to entry is the possibility of a drop in prices of similar goods. For the past few years, Lululemon has been able to sell nearly all of its inventory at no discount, due to a deliberate strategy to lower supply and entice customers. However, in recent quarters, the company’s sale section has been expanding, and many so-called “less-trendy” leggings go for as low as $60. Whether this new pricing strategy feeds Lululemon’s profitability is yet to be determined.

Given the current political climate, the possibility of U.S-China trade tensions affecting profitability is a valid concern. However, in its most recent quarterly report, Lululemon claims that only 6% off its total inventory would be affected by import tariffs; it has recently pushed to diversify its manufacturing bases, and most of which now occurs in Vietnam and Cambodia. 

Conclusion

Lululemon Athletica is a company with strong financials and an even stronger growth potential. By tapping into yet-to-be-explored markets, we expect to see Lululemon continue its emergence as a worldwide player. Its unique ability to innovate and dedication to creating quality products coupled with an overall shift towards comfortable clothing will allow Lulu to sustain its high customer retention rates. 
GoPro: Capturing Distressed Action-camera Maker’s Comeback [SOLD]

By David Shakirov

Update 03/11/21: The author recommends disposing of this stock. GoPro saw a dramatic rise in its price from the pandemic lows of $2/share to highs of $12-13 in the aftermarket last month. At this price, GoPro is almost fairly valued. However, there are concerns over management’s ability to cut operating expenses to $250m as promised (the new guidance is $305-315m) and to minimize churn on their new GoPro + subscription service. GoPro could be a $15-20 stock, but given our gain of 130% and the foreseeable risks, Insight recommends readers to sell their shares. 

In 2002, Nick Woodman strapped a cheap plastic camera onto a wristband and shipped the homemade prototype to a manufacturer in China. Twelve years later, GoPro went public at  a $3B valuation, under the premise that everyone was in the market for its action cameras. Over the course of the next four years, GoPro failed to release new cameras, began pitching itself as a “media company” and manufactured a drone that turned into a commercial disaster. Its market value plunged from $90/share to $3.38 earlier this year.

Woodman (pictured above), a major shareholder in the company, began to reorganize the business back to its roots as a consumer electronics company. He cut corporate costs drastically (OpEx margin from 68% to 38%), banked on best-in-class high end products, and offered professional video tools for its users. GoPro plans to continue on this path by expanding its TAM (total addressable market) and top line by products like VR, while improving gross margins and settling into bottom line profitability. Even better, Nick Woodman spoke out recently and said that GoPro “crushed” the Black Friday + Cyber Monday shopping season, beating last year’s revenues by a whopping +120%, capturing 97% share of the action cam market.

GoPro’s main pitch to investors is its massive operating leverage stemming from growth opportunities over the next ~3 years. GoPro plans to (1) cut its operating expenditures from current levels (~$400-500M) to roughly $250M, (2) focus on growing ASPs dramatically with a focus on high-end cameras. (3) moving DTC to expand margins, and (4) banking on high margin recurring revenues from its GoPro Plus subscription service.

Let’s dive deeper into how these growth opportunities will continue to play out:

GoPro is huge on cost cutting — an initiative to run lean and create huge operating leverage. With operating costs of ~$400m/year, Nick Woodman announced he is cutting expenditures and headcount to manufacture roughly $150m of savings per year. If only half-baked and translated to $75m of profit at a low 10x P/E multiple, this initiative alone values GoPro above its current market value.

GoPro is focusing on high end (and high margin) cameras (like the Max, which retails at $499 vs. $299 for cheaper GoPros) which significantly increases ASP (average selling price). Even better, the demand for these higher end cameras is up 90% YoY, with cameras above $300 ASP representing 95% of sales. The new Hero 8, a high end offering, had 40% more first-month sales than any GoPro offering in history. Conservatively, if high-end cameras can improve GM by 500bp, that is roughly $60m of profit to be realized.

A shift to DTC (selling on GoPro.com instead of Walmart/Target/etc.) should expand profitability significantly, as well. The company mentioned that gross margins on the GoPro website are 500-1000bp higher (north of 40%). Selling directly on the website also improves cross-sell opportunities (e.g. GoPro Plus subscription, accessories, etc.) and improves data collection on what customers want and how they shop. The margin improvement alone, if achieved at the lowest bound, should bring roughly $50M of profit into the business.

GoPro is also expanding its their new subscription platform, GoPro Plus. Plus costs five bucks a month and gives users cloud storage and small discounts on accessories and cameras. It’s a high gross margin recurring revenue stream that builds loyalty. At the current rate, subscription numbers are growing at +20% quarter-on-quarter and GoPro is guiding $60-70m of recurring revenues from this service. At conservative 70% margin, this adds $40m of profit to the business.

That’s $225m of profitability if you’re keeping count.

Some other less quantifiable but still important catalysts —

(1) Potential of expanded TAM, by venturing into VR or other verticals. Woodman cites a magnified $13B TAM in GoPro’s future.

(2) Its brand name is a significant advantage. GoPro’s new products are backed by a reputation of “best-in-class”. More generally, consumers rarely “shop around” for action cams — they simply buy GoPro (which is why it captures 97% dollar share of the action cam market).

(3) Acquisition potential is notable, as well. Major tech companies are sitting on a pile of cash (like Apple’s $250B piggy bank, for instance. Buying a best in class tech hardware company like GoPro that makes sleek and sexy electronics might make some sense. Apple is reported to release a major piece of VR hardware in a few years, while Google just bought distressed consumer electronics company Fitbit. Even an LBO from management would not surprise me.

If we add all of the potential profitability as noted above, we can back into a $225m operating income business in just a few years. We are not even including the brand name, acquisition potential, or TAM expansion. By that hyper-conservative logic, GoPro, a premium consumer electronics and technology company is now trading at 3x 2022 EBIT. That’s right, a tech company at a 3x EBIT multiple. A bargain if there ever was one. Or, as Peter Lynch would say, a four-bagger home run.

Recommendation: BUY at the current price of $4.02

Auto Partner SA: Polish Auto Parts Apparently Boring, Yet Lucrative

By David Shakirov

The “hunt for value” in US equity markets is a tough one. High valuations and economic uncertainty are some of the barriers challenging investment managers in the United States, trimming alpha to zero (or, in some cases negative). Abroad, however, frontier and emerging economies offer higher growth potential at lower multiples. These opportunities are often overlooked for mostly irrational reasons, opening a whole field of study named the “Home Bias”. Since Williams Insight is in the business of offering our take on lucrative investments, this bias opens a window to do just that.

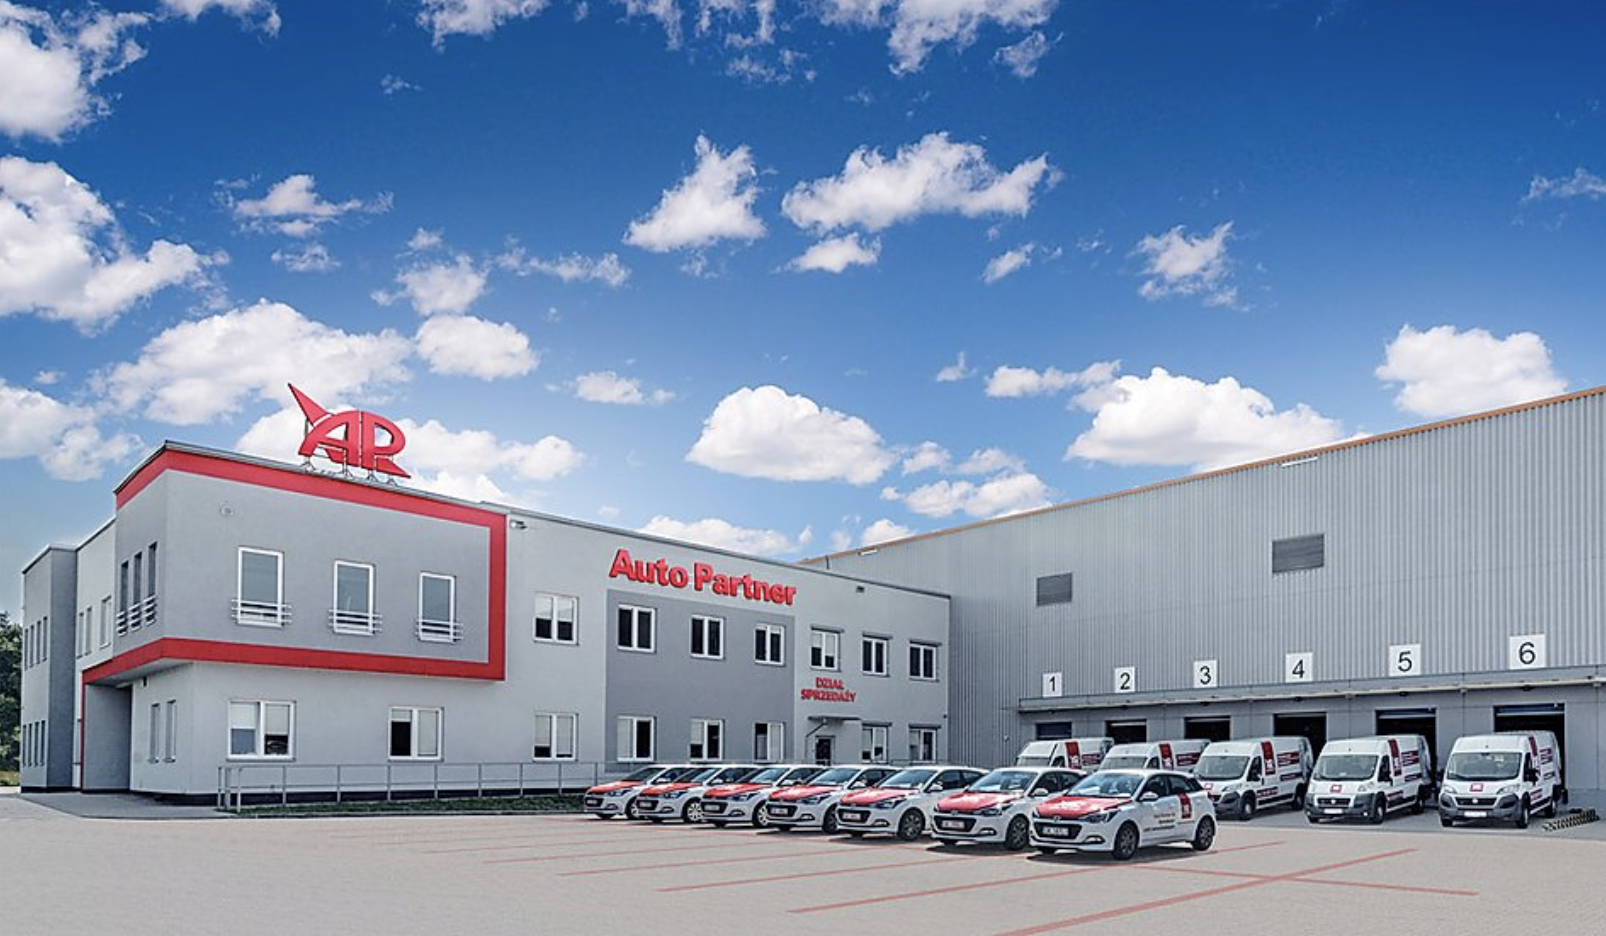
Here, I’ll cover “Auto Partner SA”, a Polish auto parts distributor that is a fast grower, trades at attractive valuations, and should reap considerable gains for investors even in conservative profitability outlooks. Founded in 1993, Auto Partner’s business focuses on selling auto parts for engines, transmissions, suspensions, lighting, etc. to mechanical shops around Europe, while taking advantage of an incredibly fragmented industry segment.

The Polish Backdrop 

 Auto Partner’s business is centered around Poland (its equity trades on the Warsaw Stock Exchange), although some of their operations are international in countries like Czechia, Austria, and Germany. The Polish economy, although relatively obscure to US retail investors, is one of the best localities for global investing. Poland, for instance, did not contract during the 2008 recession, and grew 5.1% in 2018. It has a population of 40m people, and is the largest economy in central/Eastern Europe. FTSE Russel had the conviction to upgrade it to “developed” last year (the first country to be upgraded in 10 years). From a regulatory standpoint, Poland is a stable nation — it is a member of the EU & NATO, and has an IFRS-compliant legal/financial system. Although it is relatively obscure for American investors, it does not have the political uncertainty that occupies most other fast-growing, off the beaten path economies. I challenge readers to identify any other with 5% GDP growth, attractive valuations, and a comprehensive legal/financial infrastructure.

Source: European Commission 

Auto Partner Business Model

The car parts business is not direct to consumer, but rather, entails distributing parts from manufacturers to auto shops. Auto Partner operates warehouses that allow it to ship parts from manufacturers to its customers (70% online, 29% in-store, 1% DTC), most of whom are mechanics.

Currently, the auto parts supplier market in Poland is incredibly fragmented — Auto Partner, one of the largest auto parts supply companies, has 7-8% market share. This gives Auto Partner an incredible advantage as it picks up “stranded” customers from auto parts suppliers that are smaller and go out of business. More speculatively, this fragmentation also provides M&A potential as private equity money is flowing into Poland at record levels.

Growth, Financials, and Valuation

Auto Partner’s business has been growing rapidly since its IPO in 2016. Here are a few highlights:

 +31% revenue (3 year compounded annual growth rate)

+43% EBITDA (3 year CAGR)

+53% Net Income (3 year CAGR)

Going forward, management guidance is targeting 20-25% top line growth and possibility for improving EBITDA margins.

Now, let’s model this out as a simply EV/EBITDA multiple to see how much equity upside there is…

 If we assume a conservative growth rate of 20% (2020), 20% (2021), and 15% (2022), and ignore the potential for improving EBITDA margin, we will observe the following EBITDA numbers…

Then, if we take the EBITDA numbers and apply 6x, 8x, and 10x multiples, after adjusting for net debt, we can arrive at the 2022 Equity Upside, as seen in the right-most column.

Although you can draw conclusions for yourselves, this model showcases that if Auto Partner can maintain the current 7% EBITDA margin, exhibits growth at or below management guidance (and significantly below the historical average), all while it’s EV/EBITDA multiple (which is currently 8x) compresses to 6x, there will still be 140% of equity upside in 2022 (which is 2.4x the initial investment, or 34% annual equity returns).

Recommendation: BUY at the current price of 4.33PLN

iPic: A Thriller

By David Shakirov

There was a time decades ago, when going to the movies was a spectacular affair. Forget cramped seats, with years-old popcorn stuck in-between its cheap, polyester cloth. Or the overpriced, low quality food offerings. Nowadays, the movie theatres themselves are normally wildly empty — industry insiders cite a capacity utilization rate in the teens %. No, this is not a piece on why, or how, Netflix became a $140B company. It is, however, a speculative tale of a theatre company trying to change an otherwise boring and slowly bleeding industry. What’s in its way? The Retirement System of Alabama, of course. That is, this article will try to explore the relationship between the RSA, a $44B pension fund, and iPic, a luxury dine-in movie theatre concept that found the wrong partner in its capital intensive crusade for selling movie-goers reclining chairs, martinis and lobster rolls.

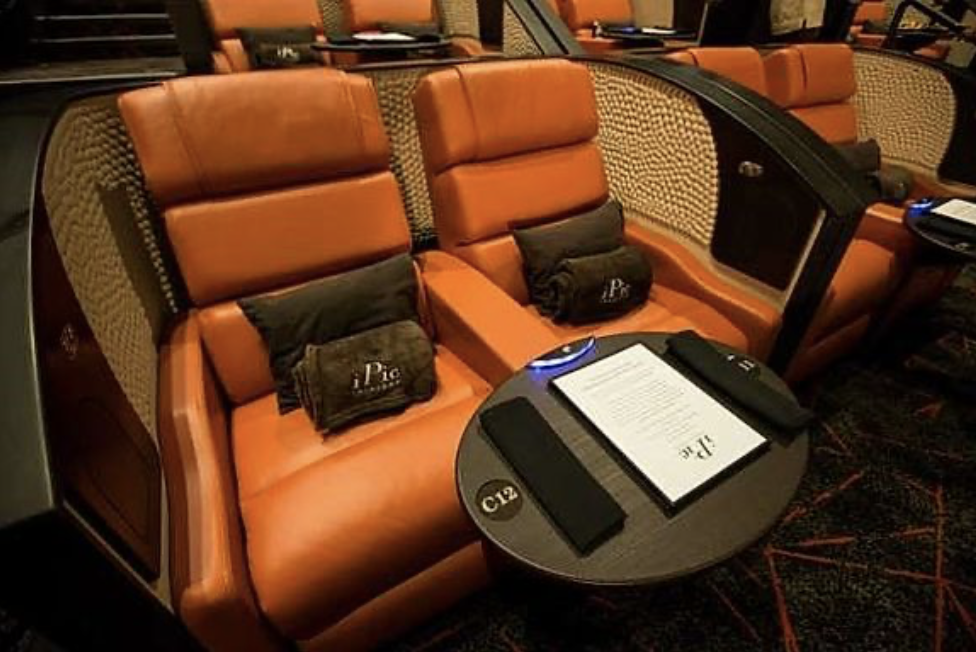
In a 2015 interview, AMC’s CFO Craig Ramsey acknowledged that the industry is slowly suffering. He noted how movie theatres, unlike most other businesses, only operate at an 11% capacity, and how, by expanding and improving its seat offerings (and increasing the ticket prices), the number of attendees grew by close to 50%. It was years before Ramsey’s realization that Hamid Hashemi was slowly developing the luxury dine-in theatre concept. Out of this came “iPic”: a concept that rapidly decreased seats per square foot, expanded the size and comfort of each seat, increased the price 2-3x, and sold restaurant quality food and booze during the film screening. The business grew, opening locations across the nation in high end neighborhoods, throwing expensive, celebrity filled launch parties, and inviting “mixologists” and chefs to populate the kitchens. While AMC struggled with $460k of annual revenues per screen, iPic enjoyed $1.65m of per screen on its most luxurious offering

At a glance, iPic seems like a ripe growth story. Inorganically, iPic wants to grow via expansion. They operate 14 theatres, with plans for 43 by 2025, and over 250 in the long run. They also want to capture 13% of the Saudi movie market after acquiring rights to open there. Each opening is financed through a long term lease, with total debt reaching average levels of $11m/theatre. In year three, iPic sees roughly 25% unlevered free cash flow returns on a new theatre, enough to pay back debtholders, and hopefully, with scale, cover its cost of goods and corporate overhead.

Organic growth is major, as well. This year, iPic plans to revamp its movie theatres to include almost 100% high end seats (think not “premium” but “premium plus”). Why? Because it found that customers prefer the more expensive offerings 4:1 to the cheaper ones. iPic gets 60% higher ticket revenues from its already high-priced tickets, and patrons spend 80% more, on average, on food and booze (win-win). Also, it’s expanding the revenue stream to include other sources, including high end advertising revenues (given its target demographic), alternative theatre revenues (renting out theatres for gaming events, for instance), etc. Overall, it’s revenue per guest is up 25% since the beginning of 2015. Even with disruptions in its theatres (during renovations) and a slow movie market in general, iPic has seen a high teen revenue growth CAGR and a 10-12% store level EBITDA margin.

Actually, its store level numbers and gross margins looked pretty good. Its unlevered returns were not bad either (again, coming in at 25%). These were the statistics that management, on its investor presentations that have since been taken down, emphasized. What these numbers fail to highlight though, is the massive debt load of the company, and its toxic corporate overhead. These two have drawn the company deep into the red, at around -25% of revenues, bottom line. As iPic’s revenues swelled from $98m in 2015 to nearly $150m in 2018, its corporate overhead doubled, along with its “other expenses” (a line item for maintenance and miscellaneous costs). These two line items alone have continuously drawn the company into the negative, excluding the interest payments (15% of revenues) on its debt.

Maybe it’s the CEO/Founder/President/Chairman’s (all the same person) $5m pay package (with cash compensation actually increasing from 2017 to 2018 as the business bled harder and harder), or the company secretary’s $3.7 comp + equity. In total for 2018, the company cites $9.4m in relation to equity-based comp. I’m not attacking a system that incentivizes executives to perform through equity-pay, but raising the point given how much overhead the company sees (why not cut the pay in half, and given the company’s proposed and believable rapid growth, have the execs put their own cash into the stock? With the stock down 90% in one year, the equity-based incentive to operate the company efficiently did not work as planned…)

In the meanwhile, the Retirement System of Alabama (RSA) promised to fund this growing, capital intensive business. I bet they heard the same-store EBITDA and unlevered FCF pitch and drank the fruit punch. I know I did. Anyways, since 2010, the RSA has funded hundreds of millions of dollars worth of CapEx, store openings, and negative EBITs, while at the same time owning class B pre-IPO equity in the company. This has now converted into a 40% equity stake, in addition to owning all of iPic’s senior debt. Yep, the Retirement System of Alabama is practically fully in charge of a luxury dine in movie theatre concept.

The RSA, just like most investors, has likely had enough. In July of this year, the RSA has declined to allow iPic to draw $10m from its $190m credit line. Why did it need the $10m? To make an interest payment on its massive debt load to … none other than the RSA. The intention is clear. In their pre-IPO filing, iPic outlines its credit agreement with the RSA as follows:

“The remaining availability under the RSA Facility requires us to achieve certain operating targets before we may borrow.” (SEC/iPic)

Last week, iPic announced its Chapter 11 bankruptcy, likely after its operating targets were not achieved and the RSA declined to extend credit. Or, as they say in Alabama, iPic “just got too big for its britches”. After the filing, the RSA lent iPic a $16m debtor in possession loan to maintain daily operations.

The business itself seems to be growing and is profitable from a gross margin standpoint. If the RSA or management can find a way to pump the brakes on corporate overhead, there could be significant operating leverage within the firm, especially as it pushes to expand from 16 to 250 theatres.

I’ve been an iPic movie and restaurant goer myself since 2016 and the business’ value prop is crystal clear. If the company emerges from restructuring, whether or not it is owned by great state of Alabama, continues with its expansion strategy, and takes massive action to cut down its overhead, it will be an investment in my portfolio. Until then, I’ll grab my popcorn and watch from the sidelines (or one of iPic’s patent pending “pod” seats) as the drama unfolds…

—

Source for Mr. Ramsey’s interview from AMC:

https://celluloidjunkie.com/2015/01/14/daily-cinema-digest-wednesday-14-january-2015/

Other sources: SEC filings and company presentations

Fiat Chrysler — From Rags to Riches [Sold]

By David Shakirov

UPDATE 11/4/2019: As of 11/4/2019, the author recommends to sell FCAU.

Even after a capital gain of 17%, from $13.78 (5/28/19 closing price) to $16.14, today, the stock continues to trade at a compressed EBITDA multiple. Unlike its competitors, FCAU runs net cash, and will likely see margin expansion as it offers higher end vehicles like the Alfa Romeo CUV, electric Maserati, and a new three row luxury Jeep. This quarter, FCAU was able to increase adj. EBIT, even as revenues and volumes shrunk (which is even more impressive with a ~15% gross margin business).

However, two issues make the investment questionable. First, holding an auto maker late cycle can prove to be dangerous. Second, the merger between FCAU and Peugeot is a source of significant uncertainty. It becomes increasingly difficult to evaluate the synergies between the two auto makers, and the benefits of such a transaction. A sell will book a 17% gain for our readers (or 7% above the S&P 500).

\\\——————————————————————————————————————————///

In the late 2000’s the American car market was in shambles. Companies including Chrysler and General Motors were pushed into bankruptcy and provided a lifeline by the federal government. Coming out of bankruptcy in 2009, Chrysler was a financially distressed corporation trying to manufacture $20,000 vehicles during the worst financial crisis since the Great Depression — what I call a hard sell. In the meanwhile, Fiat, a small Italian car marker saw an opportunity. Sergio Marchionne, the CEO of Fiat at the time (and known to be a espresso-holic and chain smoker), began expanding his stake — 20% in 2009, to 53% in 2011, and a 100% acquisition in 2014. The result  — Fiat Chrysler Automobiles N.V. (FCA).

Following the merger, FCA’s vehicle portfolio turned to be incredibly diverse and highly valuable. It included brands like Ferrari, Maserati, and Alfa Romeo (the Italian three musketeers), Chrysler (built Detroit-tough), Jeep (the legendary off-roader), and Dodge (true American muscle). FCA continues to make vehicles from minivans to Italian sports cars. Since then, its brands have seen immense growth (Maserati volumes increased 8x, its Ram trucks saw 8 years of consecutive growth, Alfa Romeo sales up by 2.6x, Jeep sales doubled, etc). Only 10 years ago, the company was in financial ruin and faced near-death.

Its 2022 master plan was unveiled last summer (one month before its CEO, Sergio, passed away) at a sentimental event celebrating the FCA success story. Its goals (and my subsequent take) include :

  • $10B investment in electric tech

    • FCA recently spent over $2B to buy emissions “credits” from Tesla to meet strict carbon-laws FOR 2020 — electrification tech is important to keep emissions low

  • Partnership with Google’s Waymo and BMW’s Aptiv for autonomous driving

    • Unlike other companies, this partnership is less capital intensive. With Waymo, FCA will provide ~60,000 Chrysler minivans for testing, while it shares resources, data, and testing with BMW

  • Maserati volumes double to 100,000 (double from 2018) and margins increase to 15% (13.8% in 2018)

    • Maserati is moving to compete with the German’s high end offerings, while its current demographic is both 5-10 years younger and has a 2x average income (there is both potential to tap into the high-mid income bracket, plus offer higher end options, all to longer-lasting customers than the competition)

  • Ram is increasing its high end truck offerings to increase its ASP

    • The brand is seeking double digit YoY volume growth and lags by $5-10k behind competitors in ASP ($50,000 vs. $56,000 for Ford, for example). Given strong loyalty data, new high end offerings should increase revenues significantly. There is also untapped potential in the Asian markets with the Ram brand

  • Expansion of Jeep as a mainstream SUV brand, with a focus on electrification

    • Historically, Jeep had an image of a tough, military off roader. Now, it sells 1 in every 17 SUVs, while it expanded production capacity by 2.4x over the last four years. With SUVs constituting most car purchases in the US, it’s natural to expand into this market. By 2022, Jeep sees industry-wide utility sales (UVs) move from 32M to 37M, and has a long term goal of 20% UV market share. It will also introduce 4 dedicated electric UV models.

  • 1.75x EBIT growth, margin increase from 6.8% to 10%, cash increase from $12B to $20B

    • Growth prospects both geographically and within each FCA brand, platform and fixed cost sharing, and its increasing net cash position should improve the company’s already positive financial situation. This may result in dividend increases (current dividend yield is 4-5%).

FCA is a growth story in an otherwise lackluster, high-fixed cost industry. It currently trades at a 7x P/E (17x industry average) and is faced with little debt (0.15 debt/assets). FCAU even trades on a 0.15 PEG. In the case of a recession, the company is well positioned financially, and in terms of product offerings, to weather the tough environment. Aside from its net cash position, it also only put up 10% of its PP&E as debt collateral, and has access to a $7B credit facility (historically stable liquidity at $20B, or 2x annual SG&A + R&D). Given the economic expansion continues, however, the company has incredible growth potential — it will continue to develop its diversified product offerings and push its untapped geographical penetration in China and LatAm, for example. Its 4.5% dividends can also provide a cushion in the case of minor capital losses.

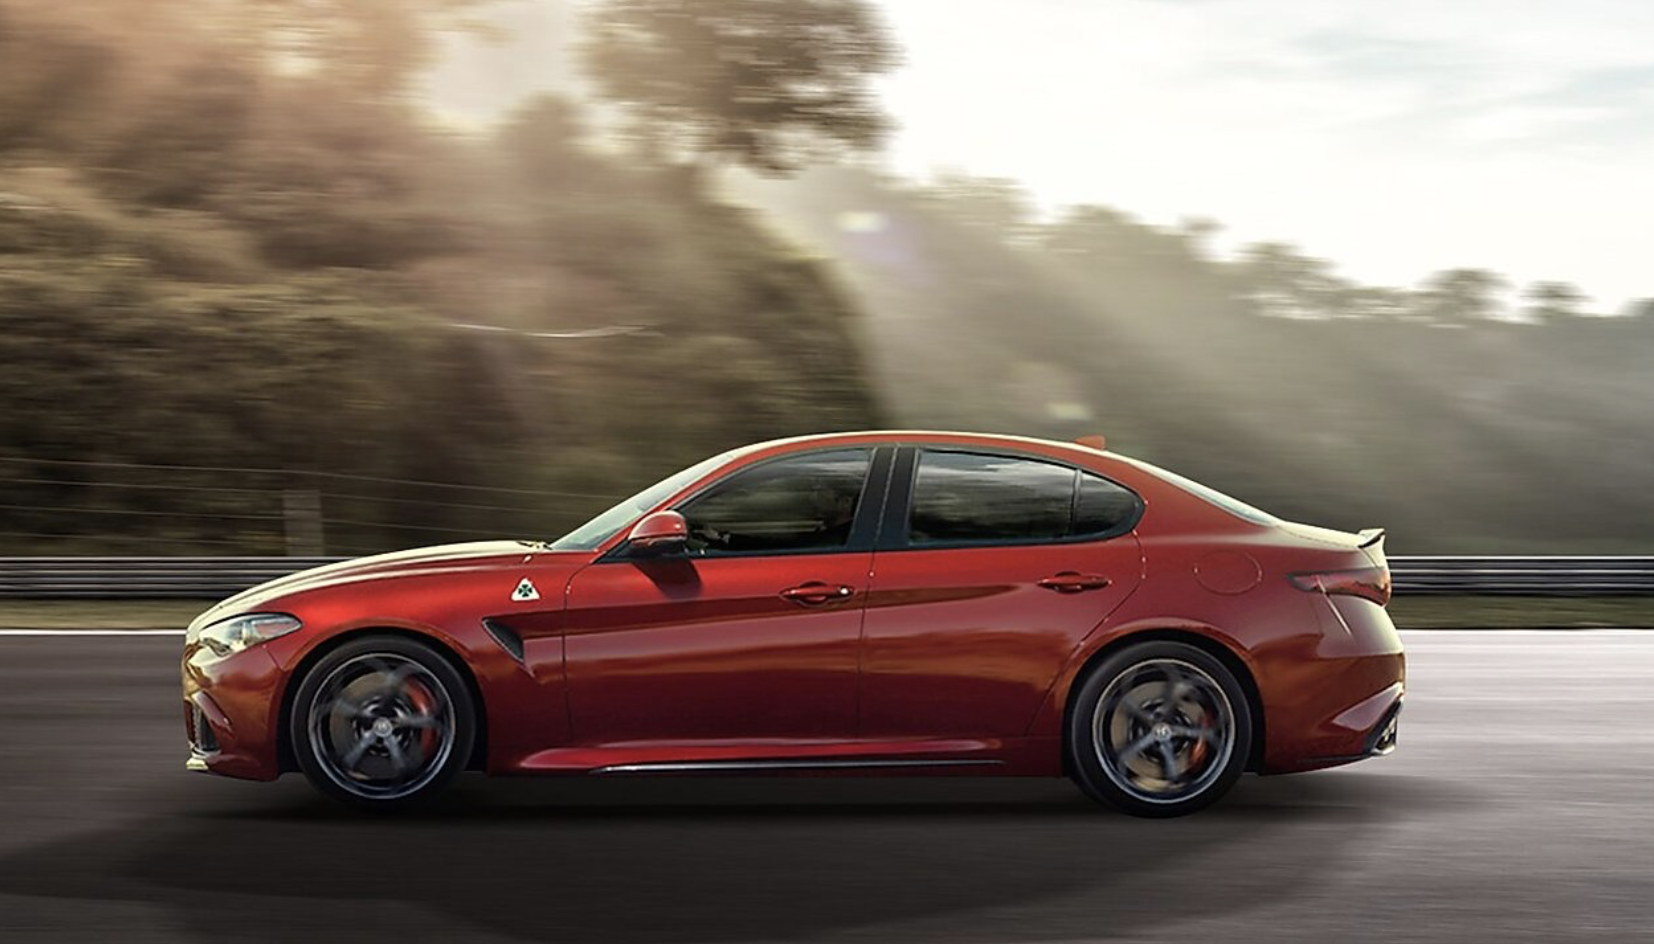
During the development of this article, I was given an opportunity to drive Alfa Romeo’s flagship sedan, the Giulia (first image) — a four door Italian rebuff of the German status quo. Why the Ramsey Alfa Romeo dealer trusted me with a $50,000 stallion is beyond the point — the vehicle drove on rails, a crystal clear step above your neighbor’s vanilla Benz. As I carved through North Jersey’s twisting and turning roads, I realized the Alfa (mind you, this is the “regular” Giulia, not the $80,000 sports version) went through near-hairpin turns at 40mph. If my anecdote is any reflection of the future, then FCA’s looks bright.

Regardless, who doesn’t want a vehicle built Detroit-tough, but with a hint of Italian love?

Recommendation: BUY at the current price of $13.78 (see updated at article header)

Revisiting Our 2019 Outlook

By Jack Brady

It’s been a pretty eventful 6 weeks since we published our initial outlook on 2019. Trade tensions have continued to ebb and flow, and the U.S. government shutdown ended uneventfully. The Fed has continued its “wait and see” approach to rate hikes, and as of Wednesday afternoon it looks like Powell may end the Fed’s balance sheet normalization at the end of 2019.

Since our 2019 outlook was always meant to be dynamic, we’re going to be revisiting a few of our “base case” assumptions about the global economy and the likely path of Fed policy that we posted back in January.

As a reminder, our three base case assumptions for 2019 were as follows:

1) Massive contraction in global liquidity.

 2) We’re late cycle.

 3) Powell is no Volcker.

 The assumption we’ll be revisiting in this post is the first, in which we assumed a steady balance sheet runoff on the part of the Fed, and no substantial easing on the part of global central banks. We’ll also be revisiting the likely impact of the Fed’s balance sheet runoff.

Our Updated View On Global Monetary Policy:

While we still don’t expect any substantial easing out of the major global central banks (we’re talking ECB and BoJ here — cuts from smaller banks such as the RBI aren’t particularly significant in our view), we are moderating our view on expected global tightening. After yesterday’s Fed minutes indicated that Powell intends to end balance sheet normalization this year, we see little reason to expect substantial tightening out of the Fed any time soon.  Just three months ago, Powell claimed that bond maturities were “on autopilot,” so this drastic capitulation on his tightening plans indicates to us that the Fed is likely going to be on hold for a while.

Remaining Balance Sheet Normalization Poses a Mere 1% Headwind to U.S. Equities: 

 We have also updated our views on the likely impact of the Fed’s balance sheet runoff this year. Initially, we had said that balance sheet normalization would be a major headwind to global markets in 2019, but we no longer believe that is the case.

According to the New York Fed, an additional $312.6 billion of Treasuries will roll off the Fed’s balance sheet by the end of 2019; so will an additional $5.5 billion of Fixed Rate Notes and an $600 million of Agency debt and TIPS. This brings total expected tightening for 2019, and for the foreseeable future, to $318 billion.

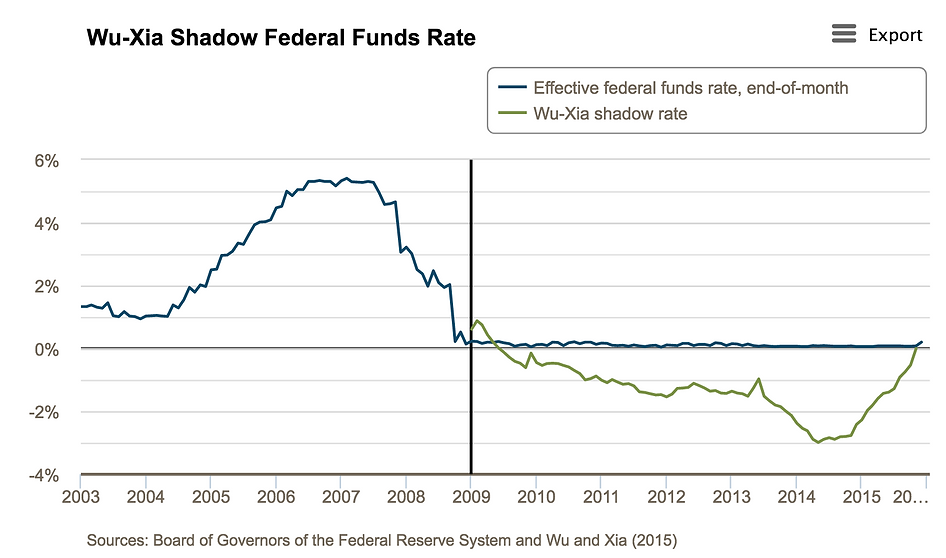
Using the so-called “shadow Federal Funds Rate” model developed by Wu & Xia at the Atlanta Fed, we have attempted to back out a reasonable value to assign to quantitative tightening, in terms of equivalent Federal Funds Rate hikes.

If we assume this model is correct, then the peak of the Fed’s $3.5 trillion Quantitative Easing program that ran from 2009 to late 2014 corresponded with a “shadow rate” of -3% (see below). With the Fed Funds rate pinned at zero that entire time, one can assume that $3.5 trillion of quantitative easing equated to roughly 12 rate cuts, so about $290 billion dollars of quantitative easing is needed to replicate the effect of one rate hike. Ignoring the fact that quantitative easing likely experiences diminishing marginal returns, we estimate that $290 billion of quantitative easing equates to approximately one rate cut, and vice versa.

Note that the so-called “Shadow Rate” bottomed out at -3% in late 2014, coinciding with the peak of the Fed’s QE program. Source: Federal Reserve Bank of Atlanta

Note the Fed’s balance sheet peaked at roughly $4.4 Trillion in late 2014, rising from just under $900 billion pre-crisis on account of their ~$3.5 trillion QE campaign. Source: Board of Governors of the Federal Reserve System

Based on this simple estimate, the threat of the Fed’s balance sheet reduction is much smaller in size than we initially thought. The $318 billion of quantitative tightening that is scheduled for the rest of 2019 should equate to barely more than one rate hike.

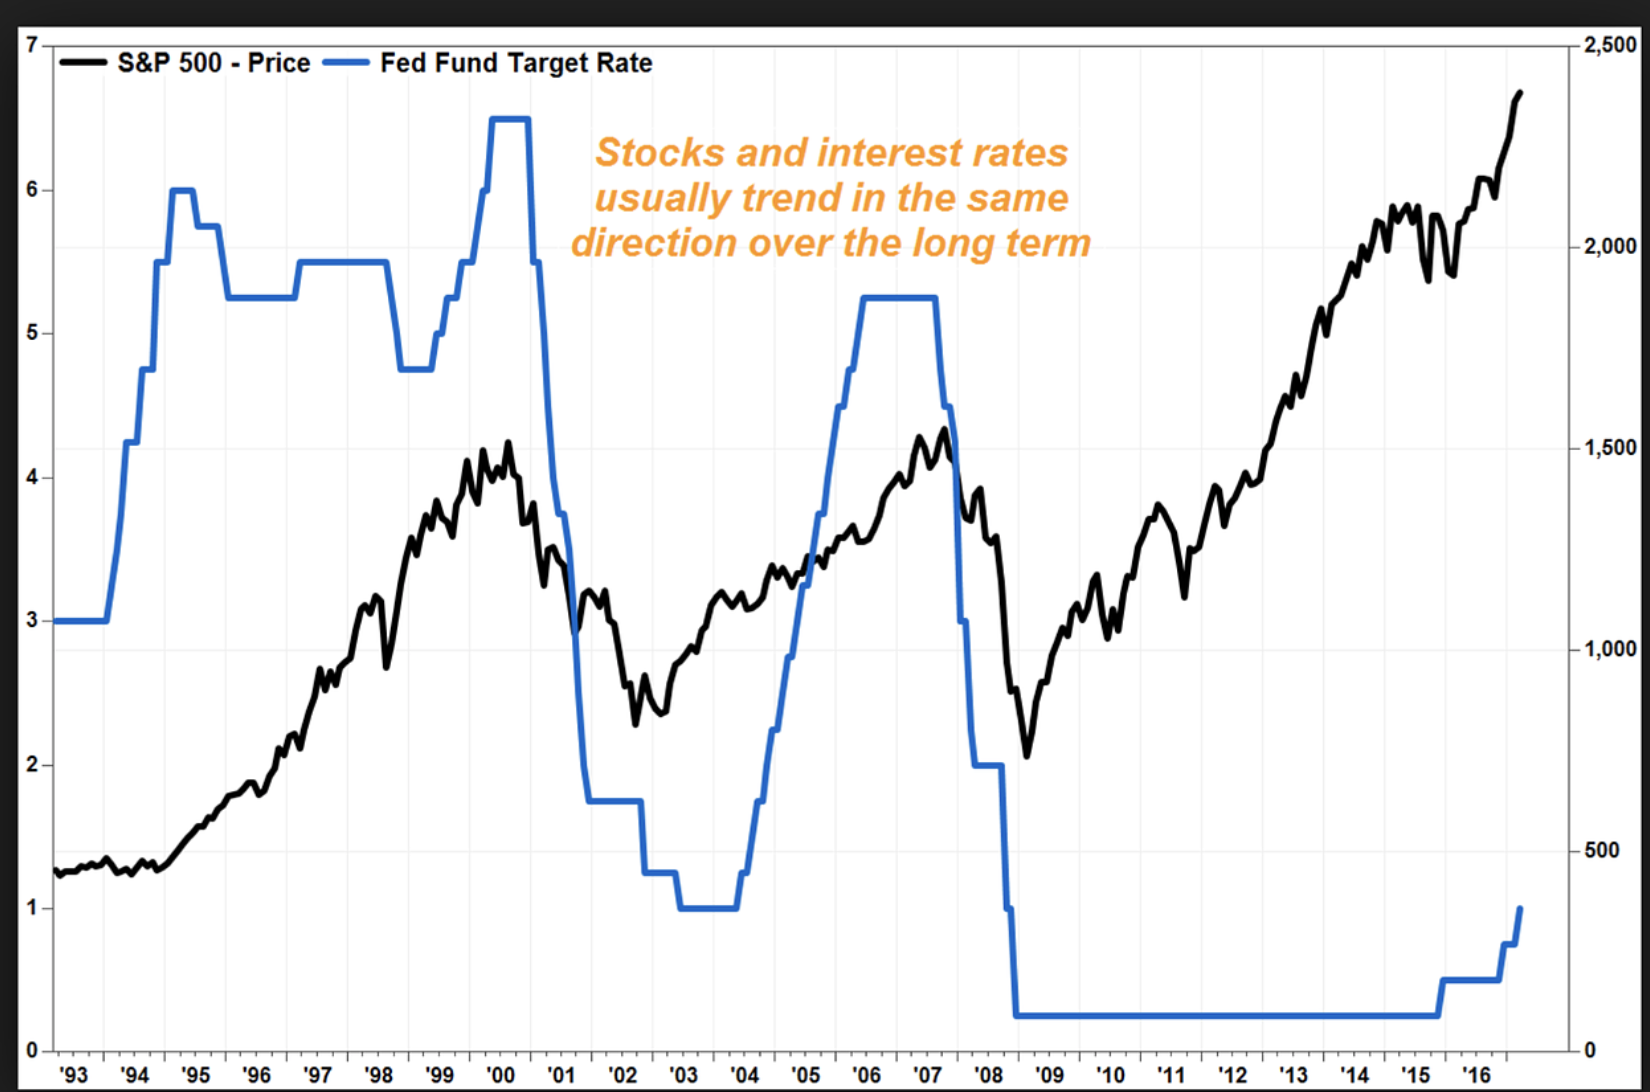
Turning back to the path of risk assets, we can use the seminal 2004 paper by Kenneth Kuttner and Ben Bernanke to determine the likely impact of this quantitative tightening on the S&P500. Their paper, which analyzes the reaction function of the stock market to Federal Reserve policy changes, indicates that a 1/4 point cut in the Fed Funds rate generally correlates with a 1% rise in the S&P500. By this logic, the $312 billion in bonds rolling off of the Fed’s balance sheet over the next 10 months represent a headwind of little more than 1% to U.S. equity benchmarks.

The bottom line is that our fears regarding a “massive liquidity contraction” were likely overblown. However, our contention that the Fed is done with rate hikes for now and that the economy is very late-cycle remains in tact, as we have seen little evidence to the contrary over the past month and a half. Our moderated expectations regarding balance sheet normalization merely mean that this rally may have a bit more room to run than we originally thought.

How Does This Change Our View? 

At the end of the day, recent developments have only strengthened our conviction that it’s time to sell this rally, or at least to dial back equity exposure significantly. The Fed’s capitulation on rate hikes and balance sheet normalization, along with broadly soft global economic data, indicates to us that the Fed is done hiking for this cycle because they think they have finally broken something. We expect the mechanical rally in stocks to continue as interest rate expectations are revised downward, followed within a few months by a recession and substantial drawdown in global equities.

We’ll conclude with a chart that we pulled from our Macro piece published in December (please ignore the commentary on this graph for the purposes of this discussion). What this chart shows is that there is typically a knee-jerk rally in the stock market after the Fed ends a tightening regime, but that the weak economic fundamentals that cause the Fed to do so eventually win out after a few months. In our minds, this market remains a rally that you want to sell, in spite of weaker-than-anticipated headwinds from quantitative tightening.

Ferrari — How Much is a Prancing Horse Really Worth? [Sold]

By David Shakirov

UPDATE (6/13/19): the author recommends selling Ferrari stock. Currently, shares trade near $160. Given Ferrari’s guidance for 2022, the stock is trading at a 30x P/E on those numbers, or a 50x+ P/E on today’s figures.  Macroeconomic headwinds may still push down its equity price in the next 12-18mo, though Ferrari NV’s underlying business will likely not be impacted as severely as most corporations.

Insight readers will book considerable capital gains: since the article’s publishing just 5 months prior, Ferrari stock has climbed 40%, or 31.2% above the S&P 500. 

\\\—————————————————————————————————///

In my last article, I spoke about Ford — an international behemoth with revenues of $150B+, low margins, distressed investor sentiment, and production numbers of over 6 million cars per year. Ferrari is also a car company, is publicly traded on the NYSE, and starts with the letter “F”. That’s where the similarities end.

Here’s why Ferrari is so interesting — unlike traditional car companies, Ferrari has immense control over its top line and customers. More specifically, Ferrari admits to limiting production of its vehicles significantly below demand to enforce an aura of exclusivity, luxury, and brand image. The latter, Ferrari admits, is crucial to its business. However, how can a publicly traded company answer to Wall Street’s insatiable appetite for GROWTH? Ferrari’s medium-term solution is to grow its product lines (sports cars, GTs, and Purosangue, or SUV) and expand its demand base significantly, while growing supply at a meager 7-8% per year. In this way, Ferrari essentially controls their top line in the short run. The longer run issue, however, is when will its production finally reach demand, forcing the company to lower prices or lose its brand image? Ferrari’s current

valuation has limited medium term upside (more on this later), but investors may be interested in three factors — high dividend potential (when the company matures in the mid-late 2020s), international growth (in EMs, China, and LatAm), and nearly universal brand value and name recognition.

The relationship between Ferrari and its customers is highly unique. Of its car sales, 65% are to existing Ferrari owners while around 30% are to owners with at least 2 Ferraris. To be “allowed” to buy one, prospective clients are often screened by their devotion to the brand through Ferrari fan-clubs, general passion for the vehicles, financial standing, and other unknown factors. Owning a used Ferrari also helps. Then, customers ate pushed to buy the entry-level variants (such as the California or Portofino). This, combined with its undersupply strategy, could position the company to weather a recession incredibly well— they control who buys the cars, and tons of clients want them! In 2008, when Ferrari was not as prominent in LatAm, EM, China, etc. and did not offer as wide of a lineup, its auto sales slumped 10% (while the luxury performance auto market shrunk in half).

It is possible that in a mild recession, Ferrari’s production may continue to rise as even recessionary demand for its prancing horse declines, given the significant gap between supply and demand.

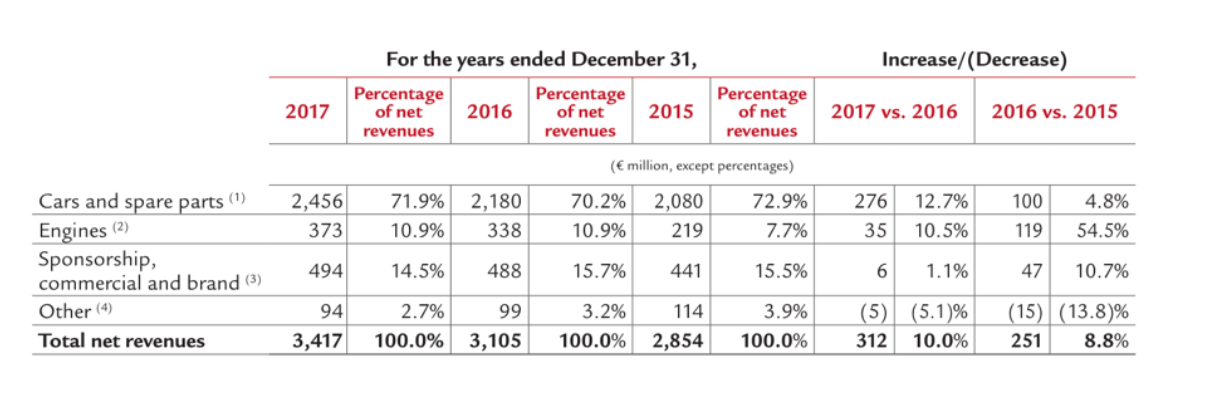
Although Ferrari is known for its car production business, this only accounts for 72% of revenues. Another 11% is engine production for Maserati (which accounts for ~80% of Ferrari’s total engine production, with the rest for Ferrari vehicles). Another 15% percent is purely based on its brand — licensing and distribution fees from selling Ferrari merchandise (think hats, shirts, and Legos), Ferrari World Abu Dhabi, and other brand-related revenues. Capital-wise, Ferrari took advantage of low rates (bonds with 25bp coupons) and secured a number of large bond offerings (it has 1.8B Euros of debt on the balance sheet, and runs net debt). Given its high margins, ability to refinance, and strong top/bottom line growth, the debt likely does not pose a significant risk to the business.

There are other important risks, however. First, international emissions regulations are pushing Ferrari into two directions. The brand could either keep buying emissions credits (by paying “clean” companies like Tesla, given Ferrari’s twelve-cylinder gas-guzzling sports cars) or begin improving efficiency. The latter strategy, which is realistic into the future, would involve hybrid motors and electrification (both of which Ferrari is trying to avoid as to not damage its brand reputation for gas-motor sports cars). Ferrari promises that in the next 3-4 years, 60% of its lineup will encompass hybrid tech and that these models will stay true to their Italian high-performance roots. Competitive risks also exist, from brands like Lamborghini, Aston Martin, Bentley, and Rolls Royce. Most of the competition is also backed by larger auto companies (Volkswagen Group in the case of Bentley and Lamborghini, BMW for Rolls Royce, etc.), which Ferrari had until its spin off and IPO in 2014. The benefits of this include better bargaining power, platform sharing, lower costs, etc. (for example, the new Lambo SUV is on the same platform as Audi’s Q7, also owned by Volkswagen). Additionally, given that 77% of Ferrari’s sales are of its lower-end V8-engine cars (which have an MSRP of $200-300,000), competition at these price points is higher. This may further discount the value of the Ferrari brand, as clients may be inclined to purchase competitive vehicles (either for lower-price or better quality). As Ferrari increases its production numbers beyond competitors due to its publicly-traded nature, it may also lose its exclusivity and touch with customers (this may not be an issue, however, if the company expands into different categories like hybrids and SUVs).

Through a DCF, I considered three cases — a base case ($116 target) where company guidance through 2022 is generally met (see the “Key Financial Targets” table), a bear case ($97 target) which includes a recession, and a bull case ($127 target) where company guidance is generally met two years early. The base case assumes a 4.7% annual growth rate of the core vehicle business (based on the CARG of the last 5 years), a 10% annual increase in Maserati’s engine demand (based on Maserati’s growth goals), and a 3% annual increase in the sponsorship arm (conservative growth). The bull case assumes the same 4.7% growth rate (since a “bull” scenario does not mean more production, given Ferrari’s exclusivity model) of the core business, but a stronger 20% y/y growth of the Maserati engine business, and slightly higher growth for the sponsorship business (somewhat conservative 5% per annum). Finally, the bear case assumes zero growth for the core business (not a decline, however, since Ferrari’s market is quite undersupplied), a 25% decline in Maserati’s business (based on luxury auto market behavior in 2008 from competitors like Mercedes/BMW), and a 20% decline in sponsorship (given a 15% decline in retail sales in 2008).

As you can see for yourself, there is not much upside or downside in the stock. However, given that they directly control around 70% of their top line results by controlling supply, the company’s performance has little downside in a recession. The short to medium term upside, however, is weak as well. Maybe I should have written this article two years ago, when Ferrari was trading at $40 (and not $110!) and had similar fundamentals. If you already own the stock (and don’t want to realize your gains for tax purposes), or are looking to invest longer term, there are a number of reasons to stay in. First, the company promises to buy back ~10% of its market cap over the next 2-3 years, has long term growth opportunities in markets like LatAm, China (where they sold only 617 cars in 2017), and other EMs, especially if it will expand its line-up to include hybrids and SUV-like vehicles. Its incredible brand value doesn’t hurt as well, while the prospect of a cash-cow business opens up the opportunity for high dividends (which are strongly considered by management for before 2022).

Overall, Ferrari is an exciting company. Unlike most car companies, it has immense control over its customers and makes exciting products. I live only a couple miles away from Ferrari’s North American headquarters and had a chance to chat with some of their engineers. One told me that Ferrari’s engineering and designing prowess (in terms of features and reliability) has improved drastically from just 3-4 years prior. Surprisingly, only two years ago, most car journalists weren’t excited about Ferrari’s vehicles and presumed that the company was relying too much on their brand to sell their cars. As a car enthusiast, I checked out the new Portofino, 812 Superfast, and some of their future offerings — Ferrari has massively stepped up products. The auto world agrees.

And who knows, maybe by buying Ferrari stock for growth you’ll be able to purchase one of their heart-stopping, pants-dropping cars down the road. If they’ll let you, that is.

General Motors 2: Electric Boogaloo

By Michael Medvedev

NYSE – GM

Price: $35.53 (Date of price: 1/9/2019)

Price Target: $45.00

P/E Ratio: 58.25

EPS: 0.61

52-week Range: $30.56 – $45.52

Market Capitalization: $49.653 billion

Shares Outstanding: 1.411 billion


Overall Markets and Auto Industry

Since 2017 there has been a dramatic transition in market conditions from long-running market stability to a drastic increase in volatility and price fluctuations as a result of trade wars, rising interest rates, and concerns around slowing economic growth. In a market with greater and more frequent losses––caused by the increase in volatility––it might be an intelligent decision to add a low beta or stable dividend stock in order to lower volatility and stabilize one’s portfolio. Since vehicle sales peaked in 2016 (Figure below), the auto industry has been a market to avoid for several reasons: investment banks downgraded the sector ratings; industry dynamics changed due to the rise of car-sharing services (Uber and Lyft); millenials are buying cars at a slower rate than previous generations. However, GM’s recent activity shows otherwise and indicates its futuristic outlook as a company prepared to thrive and spearhead the future of vehicles (namely, with electric vehicles).


 Company Overview

General Motors Company, or General Motors (GM), is an American multinational corporation which designs, manufactures, markets, and distributes vehicles (6 brands) and vehicle parts. It is the largest automobile manufacturer in the United States and one of the largests car manufacturers in the world. GM manufactures vehicles in 37 countries and has investments in multiple foreign brands.

History of General Motors

Along with most companies, the 2008 recession left GM with $31 billion in the red, making them unable to pay their suppliers and meet loan obligations or cover health care costs of its workers. However, with the Obama administration’s assistance, GM successfully survived failure by spinning out assets (creating more cash flow) and being granted billions in taxpayer funds. Soon after, they announced a government-backed Chapter-11 bankruptcy, restructured their leadership, killed off unprofitable brands, and focused more on producing fuel-efficient vehicles. With over $50 billion in government assistance – and all but around $10 billion repaid – it is safe to say that the government had a major impact on the turnaround of the auto industry. Following the recession, a successful IPO, and a steady increase in vehicle sales and net revenue fueled the company and got it back up and running… on all four wheels.

Recent Developments:

As of November 26, 2018, GM announced their plans for restructuring their business, outlining their vision for the future. Their plan includes eliminating up to 14,700 jobs (8.2% of all GM’s employees) and idling production in 5 plants. 57% of those job eliminated are in the US.  In addition GM plans to cut salaried staff by 15%, 8,100 employees and end production of several passenger cars including the Chevrolet Cruze, Volt, and Impala, the Buick LaCrosse, and the Cadillac CT6.

Why? / Catalysts

1. Preempting a possible Recession

Auto sales depend on consumer confidence, which in turn is correlated to economic cycles and markets. In a good year, light vehicle (Cars, SUVs, and Pickups) sales are expected to reach 17 million vehicles, while during a recession, sales drop to 12 million. The cycle exists because after a certain number of years, individuals need to buy a new car. An individuals income induces one to hold on to their car a little longer as opposed to re-entering the automobile market. Therefore, if income declines in all income categories, less individuals will enter the market leading to less sales. These drops in sales have a big impact on GM’s profit margins due to high fixed costs – labor contracts, factories, and imports of material. With the planned restructuring, GM benefits by lowering its break-even point (amount of units sold to break even) which would keep it profitable during a possible recession. With a prolonged expansion period and a nearing inverted yield curve, a predictable and inevitable recession seems likely in the imminent future.

2. Leader of Future Technologies

Since its birth in 1908, GM has been a top leader in its industry, producing larger variety and more efficient vehicles than its competitors. GM’s recent restructuring plan comes at time of changing consumer interests and the rise of other technologically advanced auto manufacturers (i.e. Tesla). With an increasing demand for electric vehicles (EVs) and the availability of the sustainable technology to produce such vehicles, GM is left with no choice but to adapt to these changing times in order to stay ahead of its competitors and be positioned to be a leader in future technologies. Staying profitable during a future recession will enable GM to continue research and development of the future technologies, specifically electric and self-driving vehicles. GM announced that it plans on releasing 20 new all-electric vehicles by 2023 and at least 10 in China by 2020. Also, staying profitable allows GM to continue investing in R&D for their already expensive subsidiary GM Cruise, a self-driving unit acquired in 2016. Plans of Dan Ammann, current GM president, leaving his current position and becoming CEO of GM Cruise and $5 billion in investments from SoftBank and Honda conveys how serious GM is about developing self-driving technology and what a lucrative future business it is. GM Cruise plans on launching self-driving taxis in San Francisco by the end of next year, staying ahead of Alphabet Inc’s Waymo, Uber, and Lyft and with a current evaluation of $14.6 billion, many analysts believe its long term value can triple.

Similarly, GM wants to expand future production not only in all battery powered vehicles but also Hydrogen fuel cell vehicles. The difference? While battery powered EVs take time to charge, and fuel cells EVs can be charged in minutes, last longer and are more powerful. Fuel cells make sense in certain applications where battery packs would be too big and heavy, or when recharging times are critical. Perfect customers include SUVs and long distance trucks, first responders that can not afford out of service vehicles for hours to recharge (ex. ambulances), and the US Army that have their own fuel stations and ability for manufacturing renewable hydrogen fuel. Along with its broader electric fleet of vehicles, GM has created a joint venture with Honda to mass produce fuel cells by 2020 and has made it clear that hydrogen will play a big role in its future as well, adding to GM’s commitment for the future in technology. GM’s plans are in line with the direction of the industry. GM is pioneering these radical changes and the competition is or will follow. Volkswagen AG aims to have EVs represent a quarter of its sales by 2025, Nissan and Renault will launch 12 new EVs by 2022, and BMW will launch 12 new fully electric models with mass production beginning in 2020. A reorganized GM will gain a competitive edge in the future, while also prompt its competitors, like Ford Motor Company and others, to make similar internal changes and follow in GM’s footsteps.

3. Factories were unprofitable

The likely reason that GM closed down 5 of its manufacturing plants is because they were unprofitable, or soon to be. With sedans sales falling, these plants – which specialize in producing finished sedans or transmissions – have had their production and labor hours cut. One of the factories located in Ohio builds compact Chevrolet cruze sedans, while cruze sales over the last year have fallen by more than half, it leaves GM little reason to keep the plant running while it approaches its break-even point and eventually begins to lose money when their marginal costs exceed their marginal revenue. While GM is scaling back on cars, it is not scaling back on all passenger vehicles. In fact, SUVs and trucks continue to dominate the market, accounting for two-thirds of vehicle sales in 2017. Low gas prices explain why American car buyers see little reason to not purchase a more flexible and larger vehicle. Ford similarly announced it would stop building cars in North America and would invest more capital in pickups and SUVs, while Fiat Chrysler began to phase out sedans in 2016. With sales also down in China (the world’s largest car market) for the past 5 months and on track for their first annual drop in 20 years, GM is unable to rely on China’s steady growing demand for vehicles and further explains GMs restructuring plan and closing of plants in North America, and possibly in China. The closing of the 5 plants as well comes as a benefit and obvious goal: to boost free cash flow. GM forecasts that the halt of its 5 plants will boost their adjusted free cash flow from roughly $4 billion in 2018, to $10 billion by 2021, enabling GM to focus on investing more in its future vehicles and endeavors.

4. High Costs and Trump

Since the decisions of GM, President Trump has been distressed and fueled with anger to what he believes to be betrayal. Remembering how the government saved GM from collapsing, Trump looks down upon GM’s decision to close factories and lose thousands of American jobs which counters his promises during his political campaign. In hindsight, Trump can partially be the one to blame for GMs actions due to his role in trade wars with China and urge to pass import tariffs. These high tariffs, specifically on steel and aluminum, total over $1 billion in costs for GM in 2018 and are likely to increase in the upcoming years with unclear trade war outcomes, which puts more pressure on the company to cut workers and likely pushed GM to their decision of restructuring. Similarly, Trump’s threats to strip GM of any US government subsidies may sound menacing but in reality will most likely make things worse. Cutting GM subsidies will likely make future vehicles more expensive, hurting auto manufacturing in the US. As well, higher auto import tariffs are likely to fail because they historically result in a net loss of US jobs, lower car production, offshoring of car manufacturing, and a significant hit to the US economy. Lastly, even though thousands of jobs are lost, many are offered opportunities for work in other high demand manufacturing plants.

Conclusion

We believe with GMs wise decisions of switching from an old gas powered vehicle manufacture to a new modern and future oriented company will show great success for the company and stock price in the next decade. The idea that the future of cars is coming seems as certain as ever. GM will no longer sell unprofitable vehicles just to hold market share but plans on becoming a long term leader in both EVs and autonomous vehicles. Through the next recession, GM wants to ensure it can continue to fund future advanced technology product programs, and while its business hits speed bumps as markets slow, GM has proven its well prepared to stay ahead of its competitors in the future which emphasizes its great potential within the next decade.

Vodafone: Is It Finally Time To Buy?

By Stephen Kletscher

Company Overview

Vodafone Group Plc (NASDAQ:VOD) is a global telecommunications company that operates networks in 72 countries around the world. Although it is based in Europe (74.7% of revenue), Vodafone has operations across Africa and Asia (12.7% of revenue), including a substantial presence in South Africa (12.6% of revenue).  Vodafone has the 4th most mobile customers in the world with 536 million customers. It generates $63 billion in revenue with a market capitalization of $58 billion. Vodafone has recently expanded into cloud and security services for both public and private cloud.

Investment Thesis

As of 21 December 2018, Vodafone Group Plc is trading for $19.46 per share. The price has declined 39.4% YTD and 9.2% in December 2018. It has steadily decreased in share price by 40.8% for the past five years (Figure 1). Due to this selloff, Vodafone has a sustainable dividend yield of 8.92%. This makes it one of the top yielding stocks in the market.

New management is implementing a cost efficiency savings plan that focuses on reducing operating costs and generating better returns from current infrastructure. To help offset the high fixed costs of owning and building towers, management is focusing on renting out masts by forming joint ventures with other telecommunications companies. Vodafone has reduced costs for three years in a row. Management thinks it can reduce operational costs by $1.52 billion in just Europe with an operating cost reduction target of 13% (Figure 1).

Additionally, Vodafone will not increase its dividend in the immediate future in order to provide more free cash to reduce its substantial debt of $39 billion. However, it will continue to pay the current dividend with no intention of cutting it. It is expected to increase free cash flow from $5.2 billion to $5.4 billion in 2019 driven primarily by cost cutting. Vodafone has a 1.35 ratio of free cash flow to dividend payouts, which shows that it has the cash flow to sustain the current dividend. It also has a 4.0 interest coverage ratio. Vodafone’s debt is primarily long-term and covered by an operating cash to debt ratio of 29.32%. Despite a significant amount of debt, I believe that the dividend is safe. New CEO Nick Read is the former CFO of Vodafone and has indicated that the dividend will not be cut. In fact, he has previously stated that the dividend would increase once debt returns to the lower end of a target range. Although the debt is substantial, this is typical for telecom companies with the need for large investments in infrastructure, particularly as Vodafone continues to invest in building out its 4G/5G network. Vodafone has a debt to equity ratio of 0.8, which is lower than competitors such as Verizon (1.90) and Deutsche Telekom (2.007). Vodafone also has a lower P/E ratio (10.86) than the telecom industry average (12.89) and competitors Verizon (17.91) and Deutsche Telekom (20.11). Vodafone is at a relatively cheap valuation compared to peers. It has an EBITDA multiple of 6.58 compared to a 7.17 for Verizon, 6.53 for Deutsche Telekom, and 12.07 for the telecom industry as a whole.

Previous years of significant M&A activity have caused an inefficient and overly bloated company. The company is currently struggling to deal with the issues of integrating several previous acquisitions such as KDG in Germany, ONO in Spain, and Ziggo in the Netherlands. Management plans to reduce $612 million in costs through synergies of acquired companies. Vodafone has a strong track record of cost saving synergies in previous acquisitions. New management plans to restructure the company by selling off underperforming assets and reducing costs of companies in less profitable markets. By selling off underperforming assets Vodafone will increase free cash flow to invest in more profitable areas and reduce debt.

Despite recent issues in Spain and Italy, significant EBITDA growth continues in key areas. Key markets such as the UK and Germany had half-year EBITDA growth of 12.1% and 7.3% respectively. Due to strong competition causing losses in Spain and Italy, half-year EBITDA growth was only 3% and top line growth was only 1%. Cost cutting measures in Spain and Italy should increase profitability while shifting cash towards more profitable markets. Revenue in high future growth potential emerging markets was up 7.4% in Q2 of 2018.

Investment Risks

Vodafone is based in England and is one of the largest companies in the FTSE 100. Because a majority of its business is in the Eurozone, Vodafone is sensitive to a potential “hard Brexit.”  Brexit will affect the ability of Vodafone to recruit from the broader European talent pool. A “hard Brexit” could also result in data redirection from the UK, meaning Vodafone would have to relocate data centers to somewhere in the Eurozone. The previous CEO of Vodafone had indicated that Brexit may cause Vodafone to shift its headquarters to mainland Europe, which would result in the additional costs that come with moving headquarters. However, these costs are unlikely to be too substantial because Vodafone already has substantial offices in Germany that they could expand.

In May of 2018, Vodafone agreed to a deal to purchase Liberty Global’s Germany and eastern Europe assets for $21.8 billion. This deal is now facing a full EU antitrust investigation. The EU may prevent the deal from going through, causing some uncertainty with the company’s future. The stock has performed poorly since the deal was announced, declining 31.6%. I believe that the market has priced in the deal and the substantial debt that accompanies it.

The significant debt of Vodafone is a substantial concern for the future of the company. Total debt is currently $49.79 billion. The acquisition of Liberty Global will add more to the debt. Although management has a solid plan in place to focus on debt reduction, the debt load is significant and will continue to weigh heavily on the balance sheet in the future. As mentioned previously, the debt is well covered by a 29.32% operating cash to debt ratio and 4.0 interest coverage. It also has a 1.35 FCF to dividend payouts ratio, meaning dividends are covered as well.

Recommendation

The overall recommendation Vodafone Group Plc is a buy. Although there are some reasonable concerns with Brexit and the substantial debt load of acquiring Liberty Global, I believe that this stock has been oversold. Vodafone has a solid plan to turn itself around with a new CEO focused on reducing costs and debt. It has great earnings growth in significant markets such as the UK, Germany, and emerging markets. The strong growth outlook and significant cost efficiency measures suggest a positive turnaround for the company. I have a price target of $26.48, which represents a 36% upside without counting the dividend. I think that Vodafone is a solid long-term buy and hold stock as it continues to cut costs and increase growth in high potential emerging markets. With the high dividend yield and strong growth potential, I believe that Vodafone is a compelling value opportunity.

Catalyst Biosciences: Buy Below Cash and Get The Patents For Free

By Nilay neelaveni and Osamah Qatanani

Introduction:

 Many investors are likely to remember 2018 for its ups and downs. In the US markets right now, it is hard to find safe places to invest where even the safest DOW equities have taken a precipitous plunge (Since the selloff in October and as of today, Goldman Sachs (GS) lost 18.2%, Exxon Mobile (XOM) fell 11.5%, and FedEx (FDX) tumbled nearly 25%. The Federal Reserve’s decision of raising interest rates coupled with the growth in the CBOE Volatility Index (VIX) further worry investors who are already concerned over where we are in the business cycle.  Given a bearish outlook on the market, an attractive investment may become harder and harder to find. Catalyst Biosciences (CBIO), however, is an interesting investment opportunity due to its promising science and unique financial situation.

 Our Opinion:

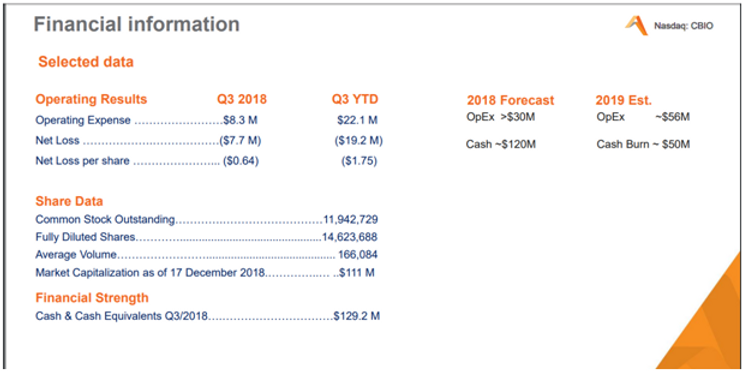
 CBIO’s investment potential stems from two important factors. Like any pharmaceutical company, CBIO is valued by the overall success of the drugs that it creates. It’s main product, MarzAA, and its second, DalzAA, are the two main drugs that make up its valuation. We’ll delve into the specifics of both of these drugs and their potential below. The second factor, the more interesting one, is its finances (In fact, we debated for a while whether the science or the finance was more interesting, so we went with the more senior opinion). CBIO currently has ~$130 Million in cash on its balance sheet. However, it’s only trading at a $113 Million valuation; that’s 13% below its value in cash holdings. Hence, not only is there the opportunity to invest while its at a low valuation, you are also being paid to own exposure to its drug pipeline.

How MarzAA Works:

If the intriguing financial situation is not convincing enough, the science behind Marzeptacog Alfa (MarzAA), CBIO’s flagship drug, certainly speaks for itself. MarzAA is unique in the way it subcutaneously (SQ), meaning self administered shots into the belly, treats hemophilia A and B, a disease that does not allow red blood cells to clot properly. The alternative method of Intravenous Therapy (IV) is often very inconvenient for hemophilia patients. For example, Sami, a friend and hemophilia patient, said: “When I was younger, it was very difficult to meet up with friends because of the long and tedious IV process done in a Children’s Hospital 20 miles away from me. It would take out so much time from my day and it also left me with needle scars that would embarrass me in school.” Sami and so many other hemophilia patients would greatly prefer this style of treatment than the standard IV process.

Digging Through MarzAA’s Scientific Results Jargon:

After people with hemophilia use MarzAA in regulated amounts, their annual bleed rate (ABR) went from as high as 28 (where 22% of their day consisted of bleeding) to as low as 0 (a 90% reduction in ABR).

Source: catalystbiosciences.com. The red bars are pre-treatment ABR and the green bars are during treatment.

Following the successful set of trials, the Food and Drug Administration (FDA) gave MarzAA an Orphan Drug Designation (2017). An Orphan Drug Designation is given to drugs that have proven to be safe and effective in preventing rare diseases, and have also been evaluated by the Senate.

How DalcAA Works:

CBIO is not a one-trick-pony. It has not one but two star products in its pipeline! Because hemophilia severity is greater when there is a deficiency in Factor IX (FIX), CBIO is also working on the production Dalcinonacog Alfa (DalcAA) to regain FIX activity.

DalcAA Has Its Own Scientific Results Jargon:

While DalcAA also shows great results of maintaining FIX activity at about 12% (which is about average), there was a snag in the plans the summer of 2018 when two subjects developed neutralizing antibodies (nAb) to the drug. This means the subjects’ immune systems were unable to accept DalcAA, simultaneously leaving them untreated. Further research indicated they are cousins and thus have similar genotypes. Many different tests indicated the drug itself has a low response index (RI) at around .18; a low RI indicates inability of antibodies to react against DalcAA. Another immunogenicity risk assessment put DalcAA at -42.54, which is well below the average mark at 0. Essentially, all the tests say DalcAA causing nAbs was very unlikely. So then, why did these cousins react to DalcAA?

After more research, it was determined that there is a small class of people with a G128A mutation that affects less than 100 registered people in America; this means these people cannot use DalcAA. Furthermore, after several tests, ex-FDA determined that the steps CBIO took were comprehensive enough to take this drug to the next stage, Phase 2b. This Phase 2b would take into account a greater sample size to ensure the drug’s effectiveness at a greater degree. Even then, FDA and this time Europe gave DalcAA an Orphan Drug Designation (2017) for its great potential. Future tests will be done with a greater sample size where success is likely possible now that the error has been identified and fixed.

The Foot-In-The-Door Technique:

Though MarzAA and DalcAA have many promising results, Anti-C3 is another drug that is being researched and created that will hopefully be used to treat Dry Macular Degeneration (fatty deposits under the retina that cause loss of vision). Anti-C3 is a testament to the depth of CBIO’s pipeline.

FDA Process Status:

CBIO is moving quickly in its process of acquiring a FDA approval. For MarzAA, CBIO hopes to get its FDA approval by Q4 in 2019. For DalcAA, however, they are not on track for receiving FDA approval in 2019. On the other hand, the two drugs should receive approval from all major international associations of Hemophilia by Q3 of 2019, where most of these associations have already expressed approval in 2018. Thus, I feel there should be no fear of the delay in DalcAA’s FDA approval.

People:

CBIO’s executive team has leaders from different parts of the business giving the company a cross functional experience in the product development, FDA process management, corporate finance, and new product rollout.

Dr. Nassim Usman, PhD-President and CEO:

Dr. Usman has twenty-six years of experience in biotech field in the areas of hematology area working in institutions such as MIT, RPI, Sirna Therapeutics.

Dr. Howard Levy,  MBBCH, PhD, MMM – Chief Medical Officer:

Dr. Levy brings eighteen years of Hematology experience to the company. His past experience in biotech and pharma leaders such as Lilly, novo nordisk, CSL, and Sangart will help in the clinicals stages of the product and while addressing FDA process.

Fletcher Payne – Chief Financial Officer

Mr. Payne brings twenty six years of field and financial experience to the company. His past experience includes companies such as Abgenix, Dynavax, Cell Genesys, and Rinat. His biotech experience and financial industry insights will help with securing the CBIO’s finances.

Mr. Andre Hetherington, SVP Technical Operations, Dr. Gant Blouse, VP Translational Research, and Jeffrey Landau, VP Business Development bring twelve to twenty years of industry experience to give the company a strong framework to execute the business.

Financials:

In such a flummoxed state of financial markets, a lot of good investments are being bid lower. CBIO is not immune to the market’s shellacking. However that has created a great entry point into CBIO at the current financial levels. Although full approval for the company’s primary product, MarzAA, and the much bigger product (by market size) DalcAA are yet to get full FDA approval, the science and path towards approval from the analysis shows great promise.

Source: catalystibiosciences.com; December 17, 2018.

With product future on track, the company’s financials are not bad either. Funding of approximately $50MM to support product trials and FDA approval towards the end of the FY 2019 is secured due to the cash and cash equivalents of approximately $129MM. With a cash burn rate of $50MM per year, the company can comfortably complete the expected milestones with ease. At the end of the day, an investor into CBIO is basically getting paid to own exposure to its drug pipeline which in of itself is promising.

Institutions hold approximately 77% of shares giving the equity some strong backing from top investors such as Acuta Capital Partners LLC, Nexthera Capital LP, Blackrock Inc., Point72 Asset Management, L.P., and Renaissance Technologies, LLC. [reference: Yahoo Financials]

If the results for the Phase 2B trial turn out to be stronger than expected, a big pharma might step in to invest in the company for their 133 patents all across the globe and the future market share on the unique drug and delivery mechanism for all age groups, giving CBIO a boost in market value. The progress in trials also gives other investors an opportunity to take a stake in the company at its infancy before the end of year 2019 heading towards final FDA process.

So what does the upside look like from here? If either MarzAA or DalcAA show the potential to be a fully approved product, CBIO’s fundamental value is much higher than it is now. Orphan drug manufacturers, such as CBIO, often receive premium valuations (take Sanofi’s $11B acquisition of Bioverativ in early 2018, a 9.5x premium multiple of Bioverativ’s valuation pre acquisition). If we assume MarzAA and DalcAA each have the potential to be a $200M/year drug, a relatively modest 5x sales would support a billion dollar valuation for either assets. Risk adjusted and discounted back to present value (10 years at 10% discount rate is about a 60% discount), we have $400m in un-risk adjusted PV. This means that if CBIO can convince investors that one of their two drugs has a 25% chance of making it to market, then the market valuation should increase by $100m, or double in value.