Catalyst Biosciences: Buy Below Cash and Get The Patents For Free

By Nilay neelaveni and Osamah Qatanani

Introduction:

 Many investors are likely to remember 2018 for its ups and downs. In the US markets right now, it is hard to find safe places to invest where even the safest DOW equities have taken a precipitous plunge (Since the selloff in October and as of today, Goldman Sachs (GS) lost 18.2%, Exxon Mobile (XOM) fell 11.5%, and FedEx (FDX) tumbled nearly 25%. The Federal Reserve’s decision of raising interest rates coupled with the growth in the CBOE Volatility Index (VIX) further worry investors who are already concerned over where we are in the business cycle.  Given a bearish outlook on the market, an attractive investment may become harder and harder to find. Catalyst Biosciences (CBIO), however, is an interesting investment opportunity due to its promising science and unique financial situation.

 Our Opinion:

 CBIO’s investment potential stems from two important factors. Like any pharmaceutical company, CBIO is valued by the overall success of the drugs that it creates. It’s main product, MarzAA, and its second, DalzAA, are the two main drugs that make up its valuation. We’ll delve into the specifics of both of these drugs and their potential below. The second factor, the more interesting one, is its finances (In fact, we debated for a while whether the science or the finance was more interesting, so we went with the more senior opinion). CBIO currently has ~$130 Million in cash on its balance sheet. However, it’s only trading at a $113 Million valuation; that’s 13% below its value in cash holdings. Hence, not only is there the opportunity to invest while its at a low valuation, you are also being paid to own exposure to its drug pipeline.

How MarzAA Works:

If the intriguing financial situation is not convincing enough, the science behind Marzeptacog Alfa (MarzAA), CBIO’s flagship drug, certainly speaks for itself. MarzAA is unique in the way it subcutaneously (SQ), meaning self administered shots into the belly, treats hemophilia A and B, a disease that does not allow red blood cells to clot properly. The alternative method of Intravenous Therapy (IV) is often very inconvenient for hemophilia patients. For example, Sami, a friend and hemophilia patient, said: “When I was younger, it was very difficult to meet up with friends because of the long and tedious IV process done in a Children’s Hospital 20 miles away from me. It would take out so much time from my day and it also left me with needle scars that would embarrass me in school.” Sami and so many other hemophilia patients would greatly prefer this style of treatment than the standard IV process.

Digging Through MarzAA’s Scientific Results Jargon:

After people with hemophilia use MarzAA in regulated amounts, their annual bleed rate (ABR) went from as high as 28 (where 22% of their day consisted of bleeding) to as low as 0 (a 90% reduction in ABR).

Source: catalystbiosciences.com. The red bars are pre-treatment ABR and the green bars are during treatment.

Following the successful set of trials, the Food and Drug Administration (FDA) gave MarzAA an Orphan Drug Designation (2017). An Orphan Drug Designation is given to drugs that have proven to be safe and effective in preventing rare diseases, and have also been evaluated by the Senate.

How DalcAA Works:

CBIO is not a one-trick-pony. It has not one but two star products in its pipeline! Because hemophilia severity is greater when there is a deficiency in Factor IX (FIX), CBIO is also working on the production Dalcinonacog Alfa (DalcAA) to regain FIX activity.

DalcAA Has Its Own Scientific Results Jargon:

While DalcAA also shows great results of maintaining FIX activity at about 12% (which is about average), there was a snag in the plans the summer of 2018 when two subjects developed neutralizing antibodies (nAb) to the drug. This means the subjects’ immune systems were unable to accept DalcAA, simultaneously leaving them untreated. Further research indicated they are cousins and thus have similar genotypes. Many different tests indicated the drug itself has a low response index (RI) at around .18; a low RI indicates inability of antibodies to react against DalcAA. Another immunogenicity risk assessment put DalcAA at -42.54, which is well below the average mark at 0. Essentially, all the tests say DalcAA causing nAbs was very unlikely. So then, why did these cousins react to DalcAA?

After more research, it was determined that there is a small class of people with a G128A mutation that affects less than 100 registered people in America; this means these people cannot use DalcAA. Furthermore, after several tests, ex-FDA determined that the steps CBIO took were comprehensive enough to take this drug to the next stage, Phase 2b. This Phase 2b would take into account a greater sample size to ensure the drug’s effectiveness at a greater degree. Even then, FDA and this time Europe gave DalcAA an Orphan Drug Designation (2017) for its great potential. Future tests will be done with a greater sample size where success is likely possible now that the error has been identified and fixed.

The Foot-In-The-Door Technique:

Though MarzAA and DalcAA have many promising results, Anti-C3 is another drug that is being researched and created that will hopefully be used to treat Dry Macular Degeneration (fatty deposits under the retina that cause loss of vision). Anti-C3 is a testament to the depth of CBIO’s pipeline.

FDA Process Status:

CBIO is moving quickly in its process of acquiring a FDA approval. For MarzAA, CBIO hopes to get its FDA approval by Q4 in 2019. For DalcAA, however, they are not on track for receiving FDA approval in 2019. On the other hand, the two drugs should receive approval from all major international associations of Hemophilia by Q3 of 2019, where most of these associations have already expressed approval in 2018. Thus, I feel there should be no fear of the delay in DalcAA’s FDA approval.

People:

CBIO’s executive team has leaders from different parts of the business giving the company a cross functional experience in the product development, FDA process management, corporate finance, and new product rollout.

Dr. Nassim Usman, PhD-President and CEO:

Dr. Usman has twenty-six years of experience in biotech field in the areas of hematology area working in institutions such as MIT, RPI, Sirna Therapeutics.

Dr. Howard Levy,  MBBCH, PhD, MMM – Chief Medical Officer:

Dr. Levy brings eighteen years of Hematology experience to the company. His past experience in biotech and pharma leaders such as Lilly, novo nordisk, CSL, and Sangart will help in the clinicals stages of the product and while addressing FDA process.

Fletcher Payne – Chief Financial Officer

Mr. Payne brings twenty six years of field and financial experience to the company. His past experience includes companies such as Abgenix, Dynavax, Cell Genesys, and Rinat. His biotech experience and financial industry insights will help with securing the CBIO’s finances.

Mr. Andre Hetherington, SVP Technical Operations, Dr. Gant Blouse, VP Translational Research, and Jeffrey Landau, VP Business Development bring twelve to twenty years of industry experience to give the company a strong framework to execute the business.

Financials:

In such a flummoxed state of financial markets, a lot of good investments are being bid lower. CBIO is not immune to the market’s shellacking. However that has created a great entry point into CBIO at the current financial levels. Although full approval for the company’s primary product, MarzAA, and the much bigger product (by market size) DalcAA are yet to get full FDA approval, the science and path towards approval from the analysis shows great promise.
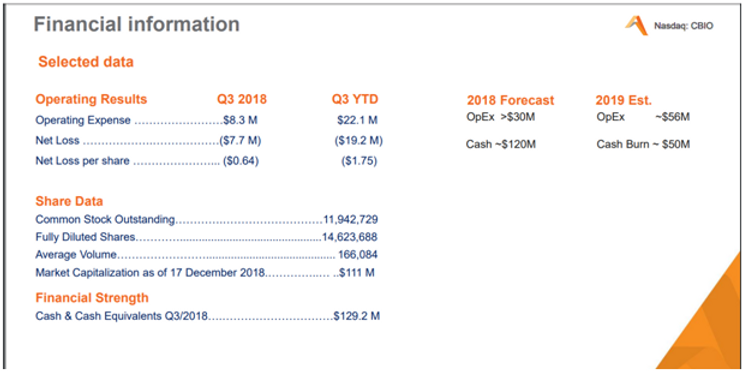
Source: catalystibiosciences.com; December 17, 2018.

With product future on track, the company’s financials are not bad either. Funding of approximately $50MM to support product trials and FDA approval towards the end of the FY 2019 is secured due to the cash and cash equivalents of approximately $129MM. With a cash burn rate of $50MM per year, the company can comfortably complete the expected milestones with ease. At the end of the day, an investor into CBIO is basically getting paid to own exposure to its drug pipeline which in of itself is promising.

Institutions hold approximately 77% of shares giving the equity some strong backing from top investors such as Acuta Capital Partners LLC, Nexthera Capital LP, Blackrock Inc., Point72 Asset Management, L.P., and Renaissance Technologies, LLC. [reference: Yahoo Financials]

If the results for the Phase 2B trial turn out to be stronger than expected, a big pharma might step in to invest in the company for their 133 patents all across the globe and the future market share on the unique drug and delivery mechanism for all age groups, giving CBIO a boost in market value. The progress in trials also gives other investors an opportunity to take a stake in the company at its infancy before the end of year 2019 heading towards final FDA process.

So what does the upside look like from here? If either MarzAA or DalcAA show the potential to be a fully approved product, CBIO’s fundamental value is much higher than it is now. Orphan drug manufacturers, such as CBIO, often receive premium valuations (take Sanofi’s $11B acquisition of Bioverativ in early 2018, a 9.5x premium multiple of Bioverativ’s valuation pre acquisition). If we assume MarzAA and DalcAA each have the potential to be a $200M/year drug, a relatively modest 5x sales would support a billion dollar valuation for either assets. Risk adjusted and discounted back to present value (10 years at 10% discount rate is about a 60% discount), we have $400m in un-risk adjusted PV. This means that if CBIO can convince investors that one of their two drugs has a 25% chance of making it to market, then the market valuation should increase by $100m, or double in value.
All Small Businesses Lead to… Square?

by Saamia khan

Up until late last year, Square (SQ) enjoyed massive growth in its share price in 2018; reaching a peak of nearly $100/share in late September, its share price quickly plummeted nearly 50% to $51/share by late December. Square’s mobile payment processing apps, credit card readers, small business organizational tools, and even a children’s book (My First Bitcoin and the Legend of Satoshi Nakimoto) among other products have made Square a company to put on the watchlist. Small businesses like coffee shops, restaurants, and hair salons have been swift to adopt Square’s recognizable white stands that turn iPads into payment processors. While this share price volatility coincided with an overall market downturn, and is typical of an early stage growth stock, I would argue that Square’s current share price of $66/share is overvalued. Depending on the economy’s health in the medium term, shares could decline to as low as $40/share.

Square hopes to become a one-stop-shop for small businesses by creating an entire financial ecosystem. In pursuit of this goal, the company has rolled out an array of innovative hardware and software products to help facilitate small business operations. Its original product, the Square Reader allows businesses to accept credit card payments on the go. Used concurrently with the Square Dashboard app, owners can track and compare real-time sales data. Square Appointments combines the payment system with easy access to managing bookings and clients. Square has even started to dabble in high-end food delivery services with the acquisition of the startup, Caviar. The theory goes that if a business adopts even one of Square’s products, it is likely to try others as well. Square hopes to increase its online presence, and to this end, it has acquired the website creation company, Weebly.

Within the past few quarters, Square started offering loans to small businesses, coining the name Square Capital. In the last year, they have seen a 34% increase in loan volume. More recently, Square has applied to become a licensed bank, allowing the company to have greater autonomy with loaning while also allowing them to take deposits. Jacqueline Reses, the would be chairman of the bank said in a statement, “Square Capital is uniquely positioned to build a bridge between the financial system and the underserved, creating access for small businesses to both capital and the economy.” In giving out loans, Square may be doing a favor to small businesses that generally have trouble financing their operations through other means. For Square however, this spells trouble should these loans perform poorly; according to the U.S. Small Business Administration (SBA), only about 50% of small businesses survive longer than five years, and more than 1 in 6 SBA-backed loans went into default between 2006 and 2015.  In loaning funds primarily to small businesses, Square exposes itself to an unparalleled risk.

Evidently, Square has created a detailed organizational plan aimed at small businesses with its hardware and software products and loans. However, what’s concerning lies in the fact that Square is starting to look a lot more like a bank than a tech company. Traditionally, the market is willing to pay a higher multiple of earnings for tech companies. Square’s current valuation may reflect this sentiment. And although revenue has increased through each quarter of 2018, earnings have only just edged into positive territory in the third quarter. This points to the fact that Square’s share price may currently be overvalued.

The company’s success relies heavily on booming sales in the small business industry. Not only is this a somewhat worrying business model in the face of a looming recession (economists forecast a 25% probability of a recession within one year), with a Beta of 4.25, the company is especially vulnerable to market swings— Square’s share price has dropped almost 50% since its peak in late September 2018— coinciding with an overall weak S&P 500 performance. Moreover, Square’s dependency on small businesses may result in problems in the future. Conventional wisdom says that during a recession, consumer spending decreases. Although this consumer spending drop affects all businesses, smaller companies bear a greater brunt. Figure above illustrates small businesses identifying poor sales as the “Single Most Important Problem Associated with Weak Economic Conditions.” During the most recent recession, employment decreased by 10.4% for businesses with less than fifty employees, while all other businesses saw a 7.5% decrease, a significant difference (Figure below). Although small businesses do have more flexibility in laying off workers, recessions evidently seem to accentuate small business operation difficulties, coupled with evidence of higher rates of bankruptcy. Given that Square derives much of its revenue from small businesses, a drop in consumer spending may result in unpaid loans and simply a smaller volume of sales, signaling decreasing profits for Square.

When Jack Dorsey and Jim McKelvey founded Square in 2009, its idea for an on-the-go credit card processing service aimed at small businesses was fairly novel. However, competition since then has increased. PayPal, Intuit, Capital One, and Shopify all offer quite similar products in terms of basic credit card readers. To the average small business, it is not expensive to switch credit card readers to a cheaper alternative. If a small business is not already integrated with the rest of Square’s apps like Square Dashboard and Square Appointments, there is little incentive to stick to Square if the costs are greater. To this end however, Square has tried to distinguish itself, rolling out a number of supplements to its main credit card processing terminal. Future quarters will reveal whether or not Square’s push to retain clients has proven to be a success.

Square’s focus on a niche sector of commerce— doing business with micro-merchants— may end up exposing the company to great uncertainty. Expanding its base to larger businesses may help alleviate some of this business cycle dependent risk. If Square can continue finding ways to distinguish itself from competitors, this may pay off in the long run. Nevertheless, with a view of a potential recession in the medium term, SQ is a sell.

Fortnite: A New Business Model

By Nate medow

Epic Games is a privately owned company that created the famous online game Fortnite. Fornite took the nation by storm in April of 2018 as a free downloadable game that could be played on Xbox, Playstation, PC, and mobile devices.  With over 200 million users, Fortnite generated over $2 bn for Epic Games, and is just one of the many games in the industry that generated $138 bn in 2018(up roughly 30% from 2017).

Fornite’s massive popularity brought global attention to the shifting structure of monetizing online games as well as the growing opportunities that exist in the gaming industry.  Popular games such as Madden, FIFA, and Call of Duty are bought for a one time fee which unlocks all functions for the user. This profiting method has been the dominant one throughout the history of the gaming industry.  However, Fortnite, deviated from this typical structure, offering the game as a free download.

In Fortnite, non-paying and paying users have access to the same in-game functions.  They both can play in the battle royale mode with access to the same guns. Paying users gain no competitive advantages from their payment, which is unique.  For example, in Clash of Clans, another free downloadable app, users who pay for items gain competitive advantages over those who do not, which minimizes the amount of non-paying users who play the game.  Creating advantages for paying users can hamper the growth of a games popularity due to users aversions to paying for items. Simultaneously, developers need a method of monetizing their application, and offering in game incentives in exchange for money is a popular method of doing this.  But there is a balance, and Fornite’s model seems to have found it.

Fortnite generates revenue through microtransactions—a model where users acquire virtual items with micropayments.  The first of these microtransactions that occur is the sale of “battle passes.” Fornite has seasons, which last roughly 2 months.  At the start of the season every player is at equal tiers, and they try to increase their tier(or level). As the user levels up, emotes and skins can be earned.  If one purchases a battle pass, more of these items are earned when you level up. While a non paying player can earn some of these items, it becomes significantly harder.  Moreover, there are certain items that non paying players do not have access to regardless of how many times they level up. A battle pass, which lasts one season, is currently $10.  The other way in which Fortnite uses in app purchases is through their store. This is much more common of apps, but again it differentiates in that the store offers no competitive advantages for spending money.  In the Fortnite shop users can buy v-bucks with real currency and then spend it to buy emotes, skins, and gliders.

The Fortnite model is not perfect by any means.  Companies that do adopt the Fortnite model must constantly update the game and utilize social media tools in order to keep the game popular, which can become prohibitively expensive.  Moreover, the model is particularly reliant on consistent user participation in ways that other games are not. Profits for games that charge a one time fee are impacted less from a decline in user participation, which is a large reason for why the Fortnite model is not the proper choice for every developer.  In fact, Red Dead Redemption 2 recently released via disc and brought in $725 million of revenue in the first 3 days.

While there are certainly issues with the Fornite model, it is indicative of a new method of developing profitable games, which has caused other gaming companies to look at how they can adopt the Fortnite model.  Companies that do adopt this model should increase corporate sponsorships of the coveted in-game items that users are willing to pay for, which is something Fornite did not do often. I believe Fornite could increase their profits without detracting from users game experience if they used their in-game items as platforms to advertise.  Developers could partner with fast food fast food chains and beverage companies, such as McDonalds and Coca-Cola. For example, with every Happy Meal or bottle of soda, a code for a free in-game item could be included. In this way these developers would still be able to profit off of non-paying users—one of the larger issues with this model.

As this industry continues to rapidly expand and adapt, some public companies to keep an eye on are Ubisoft(UBI.PA), Tencent(TCEHY), Activision(ATVI), EA Sports(EA), and Take Two Interactive(TTWO).

Disclaimer: the author does not personally own any of aforementioned stocks in his portfolio and does not assume any responsibility of readers’ investment decisions.

Our Game Plan for Trading a Volatile 2019

By Jack Brady

Now that the dust has settled and we’re back at school, we here at Williams Insight are publishing our “gameplan,” so to speak, for trading a volatile 2019. Think of this as our macro-view, and how we plan to trade developments in financial markets.

The difficult part about publishing beginning-of-the-year pieces is that nobody gets it exactly right. Frankly, I’ve stopped reading anything where a financial commentator claims to know anything resembling the path of risk assets. That’s why we’re referring to our inaugural commentary of 2019 as a gameplan. As in the world of sports, the world of investing moves quickly and any good “coach” (portfolio manager) needs to be able to respond to changing and unpredictable conditions to correctly deploy their assets on the field.

This piece will have two sections. First, we will lay out our base-case assumptions for 2019. Most of these have been discussed at length in other articles, so we won’t get into the “why” of these assumptions so much as the “what”.

Second, we will lay out how we plan on trading various developments that could materialize this year, based on our assumptions about the macroeconomy. Let’s get started!

2019 Base Case:

1) Massive contraction in global liquidity. This has been a favorite topic of mine, and has been discussed at length in several different articles. Suffice it to say that global financial tightening is now in full effect, and it will take nothing short of a recession to stop it. I believe this will be the key theme of 2019, in the same way it was the key theme of 2018. It’s no coincidence, in my view, that December was one of the worst months of stock performance since the Great Recession (depending on which index you track). Once the ECB stopped QE, liquidity simply began to vanish from markets.

2) We’re late cycle. Central banks are tightening, equity markets are volatile, valuations (and possible even earnings) have peaked for the cycle, most economic indicators have either peaked or are at cycle highs, and interest rates have been rising for about two and a half years with few pauses. It doesn’t take a rocket scientist to realize this cycle (which was artificially prolonged by CB liquidity which — you guessed it — is getting pulled back) is getting long in the tooth.

3) Powell is no Volcker. As we’ve seen over the past three months, Powell’s claims that he would ignore political pressure and signals from the stock market were… well they were overstated. We expect balance sheet tightening to continue, but we (like the Federal Funds Futures market) don’t have a strong view on the path of rate hikes, as they’re likely to be data dependent. Relatively easier or tighter policy from the Fed will certainly have the power to bend the edges of this cycle a bit (I’m talking months here, not years), which makes them important to consider. That being said, the writing is on the walls in the form of $50B a month in balance sheet reductions from the Fed.

What To Do About It.

So we’re late cycle. But that leaves the question of what to do about it. It is often observed that the tail end of bull markets experience the most ferocious rise in asset prices, so there’s definitely an argument to be made that one should maintain a reasonable amount equity exposure. On top of that, equities seem to be temporarily bottoming as we speak, so selling everything now might not be the best bet.

Our mantra for 2019 is simple: hold on to what you have for now, and selectively sell rallies. As we’ve pointed out before, late-cycle dynamics often create volatility to the upside, as well as to the downside. That is why we advocate lightening up on high-beta exposure when the market does happen to exhibit strength. When I say high-beta, I’m referring to volatile, economically sensitive positions that have been doing very well during this bull market and are likely to get creamed in the event of a recession. For example, I am looking to get out of my position in QQQ (Nasdaq ETF) at a reasonable level.

What constitutes a reasonable level is tricky, but we have a few helpful tips in mind.

1) Define your “target” exposure levels for the end of the year, and work towards that goal. For example, I hope to own only my core, longer term positions by the time the year is out, and park the rest in Robin Hood where I earn 3% risk free. These core positions include SDY (Dividend Aristocrat ETF), VWO (Emerging Markets ETF), and my 2-10 steepener position (shorter term, but still one of my core positions as of early December). Everything else is up for sale at the right price. Certainly this is more art than science, but here are some useful levels:

2) Begin sizing out of positions quickly if the S&P hits overbought territory (RSI over 70). This is not likely in my view, but a move up as violent as this would certainly provide an exceptional opportunity to sell.

3) Begin sizing out of positions quickly if the S&P approaches 2018 highs. Roughly 2900.

4) The tricky part is knowing when to sell if markets don’t exhibit a late-cycle mini boom. This is why it would be prudent to sell off a little bit of equities every time the S&P has a “notable” day or two. A rough metric for measuring this would be that you should sell every day Bloomberg or the Wall Street Journal has a headline about how well the markets are doing.

5) Develop your own view, and modify your portfolio accordingly. We’re better sellers right now because our bias is to be short the market. If you think that the recent correction was overblown, then buy the dip — after all differences of opinion are what makes a market! Just make sure to set up your own “guidelines” for when to sell or when to buy more.

Finally, a note on buying the dip. Since we’re on the bearish side, we’re not looking to fade 5% moves down in the S&P because we think the biggest moves in 2019 will be down. We’re currently selling our equities, collecting 3% interest on cash, and waiting for the “big dip” (Full Disclosure: this may not happen in 2019). Our “big dip” needs to check three boxes:

1) Markets fall at least 35% from their peak. Recessions (look at the last 2) typically entail a 50% drawdown, peak to trough (although how long this takes varies from several months to years). Whatever comes next will be following an unprecedented rally in equities, so it could actually be more than that 50% figure. Regardless, a dip of less than 35% is likely to be ephemeral.

2) The yield curve should steepen like crazy during the big dip as shorter term rates collapse relative to longer term yields. This is characteristic of a recessionary bear market, and will coincide with any big, career-making dip-buying opportunities.

3) People will be terrified. Even though this is totally subjective, it’s a useful metric nonetheless. The next “big dip” will almost certainly coincide with policymakers scrambling to figure out what to do, pundits declaring an inevitable “lost decade” of stock market returns in the 2020s, and President Trump going far crazier than normal. If Trump punches Powell on national TV, you have our blessing to lever up and go long.

Ford: Buy for the Value, Keep for the Dividend [Sold]

In my last article, I mentioned that tech is not the love-child of the markets anymore. If Apple is no longer “hot”, then neither is a 115-year-old American car company. I’m referring to Ford — at one point the pride of American innovation, manufacturing, and design, and now a company struggling to find their forte in the evolving car business. Investors look to sexy electric vehicle manufacturers that produce models with self-driving capabilities and gut-wrenching acceleration (ahem, TSLA). The newest 2019 Ford mom-van, unfortunately, may not hit those marks. Kidding aside, Ford’s stock (F) has suffered since 2014 — not a fun ride for those aboard. Since its $17 peak, Ford has hit bottom, as of this article’s writing, at $8.02 — a 55% price decline over 4 years (the S&P 500 has climbed nearly 30%). Investors point to an uninspired focus on autonomous driving technologies as competitors ramp up efforts in self-driving tech. International demand, especially in China (18% of business, by units), is also a concern for investors — President Trump’s tariff disagreements are not helping (however, Ford’s largest market is the United States). Contrary to investor sentiment, however, Ford is investing heavily in self-driving tech, maintains a healthy cash position, grows revenues, and pays a 7% dividend (which has been reiterated as recession-proof by management). When Ford is mentioned throughout this article, the term refers to the Ford brand, in addition to its F-series, transit van, Ford Credit, and Lincoln businesses.

Ford’s international exposure is a major concern for investors. Although revenues in all but Ford’s smallest region (Africa/Middle East) have either increased or stayed flat over the last two years (this includes Asia, Europe, South America, and North America), market share is a different story. Ford’s share in all of its regions has decreased slightly (e.g. 14% to 13.9% in North America, 9.6% to 8.9% in South America, and 3.6% to 3.4% in Asia). Given that overall sales volume was in better shape, while Ford’s market share deteriorated, a highly-competitive environment may be cited. Competition from other American brands (including GM’s Chevy/Cadillac unit, FCA’s Jeep, Dodge, Ram, and Chrysler units, and yes, Tesla) or Asian companies (i.e. Honda/Acura, Toyota/Lexus, Kia/Hyundai/Genesis) may be problematic. As a bit of car-geek myself, it’s hard to make a case for most of Ford’s models over competitors— the “Taurus” has not been refreshed for 9 years, the “Fusion” has looked the same for the last 6, while the “Flex” reminds me of a refrigerator.

Ford has two major issues with its models — an aging line-up and lack of autonomous tech. First, Ford is moving to change its model line-up entirely. It announced earlier this year that all non-SUV/truck models (minus the legendary “Mustang”) will be on their way out in North America soon, to reflect consumer preferences toward the SUV. By 2020, the company promises to reallocate $7B from sedans to SUVs, while introducing eight new or refreshed models. Ford’s existing SUV’s are all receiving refreshes either this or next year, including a sporty “Edge” (think Mustang-powered mom-van), and a full-size SUV from Lincoln that blows Cadillac’s Escalade, or its largest competitor, out of the water. The F-series pick-up truck (which is America’s best selling vehicle by volume) has recently received a major overhaul, and a brand new “Explorer” is coming out January 9th. A separate Mustang-SUV model is also in the works. Ford also continues to focus on providing electrified options for its vehicles, and promises to sell more hybrids than Toyota by 2021, although this may be a lofty goal. Given that margins on larger vehicles are often thicker as well, bottom line numbers may improve during this transformation.

Over the last 3 years, however, Ford has made a mistake by delaying its autonomous unit. While Tesla claims some of its models are already equipped to handle self-driving software, competitors like GM have raised billions for their self-driving units and promise results by the end of 2019. Ford, on the other hand, has joined the race this July and promises driverless vehicles by 2021 by creating its own unit, “Ford Autonomous Vehicles LLC”, and attracting outside investors. A two year difference seems major, but really isn’t — even if GM or Tesla release driverless models (referred to as Level 5 or 6 autonomous vehicles) by the end of next year, the adoption rates by consumers and legislative challenges will be major. Here’s a worrisome study — the percentage of people who said they would not trust a self driving vehicle increased from 40% in 2016 to 48% in 2017. As of this week, Congress also pushed autonomous vehicle legislation into 2019, a disappointing move to companies that hoped to begin testing on more public roads. Regardless of when self driving tech becomes fully developed (or legally permitted), most consumers are currently satisfied with blind-spot monitors and collision warning systems in their vehicles, although the landscape may change by 2021.


Financially, being 115 years old may be “boring”, but it certainly helps the piggy-bank. Ford’s short term liquidity (cash + short term investments) is substantial — $39B in 2017 (an $2.5B increase from 2014), while shareholder equity is $35B (an $11B increase from 2014) at a $30B valuation. GM, its direct competitor, has seen declining equity (to $35B, as well), cash and S/T investment levels 40% lower than Ford’s, a lower dividend yield, yet a higher ($40B) valuation. Furthermore, its price/sales and price/book are both lower than GM’s (40% and 32% lower, respectively). Between the two main American automotive manufacturers, Ford may trade at a more attractive valuation. To take advantage of its strong cash position, Ford has also boosted its R&D spending by 20% over the last 3 years to develop its self-driving unit and, with increasing top line and stable bottom line results, can afford to do so.

Ford Credit, and Ford’s pension liabilities may be concerns for some investors. The former provides leasing and financing tools for Ford customers, and is affected by unexpected events (i.e. repos, defaults, etc.). Over the last two years, however, this business has been stable (with mid-700 FICOs and stagnant repo rates). Ford also maintains a stable amount of reserves (0.43-0.44% of receivables) for its credit business. In terms of pension liabilities, Ford currently has a ~90% funded pension. This amounts to a $8B gap in funding, a small amount relative to Ford’s cash/short term liquidity.

Here’s the really exciting part — its 7.5% dividend, consistently paid over the last 3 years. The dividend costs Ford a touch above $2B per year, and, according to its CFO, will perpetuate in the case of a recession. This is not unlikely, given the company’s cash position and extensive credit lines. For long-term investors, whatever room is left on the downside may be cushioned through a $0.15/share quarterly “pillow” and may provide consistent fixed income even during an economic downturn over the next few years. Can we really trust Ford’s management on maintaining the dividend? On average, car sales by units in the US fall 17% during economic downturns (given data over the last 3 recessions). If Ford’s revenues decline 17% in a downturn, their bottom line would decrease by $2.9B (given a net profit margin of -11%, as it was observed in 2008). Hence, even if Ford declines 1:1 with the auto market (which, assuming Ford’s vehicles are revamped over the next few years and become more attractive than the average, may not hold true), Ford’s bottom line would decline to $4.6B, while operational free cash flows would fall 16% to $13.5B, well above the $2.5B yearly expenditure on dividends Given the fall in FCFs, we would expect the net change in cash to turn negative (-$2.4B), given data from the last 5 years. Ford’s cash/cash equivalent position sits at $40B — a cushion large enough to absorb an economic downturn seen in 2008 (even though the next downturn will most likely be less severe).

The stock has hit (as of writing) last month’s 9 year low. Given this, plus a sub-30 RSI, it is highly likely to bounce up from this level. In late January, Ford’s quarterly report is due and may be a catalyst for an upward move if it beats its cited key metrics (including profitmargins and EBIT). More importantly, its transparency about future plans in regard to autonomous vehicles or a turnaround may spur positive sentiment.

In terms of valuation, a conservative DCF scenario yields $10.50-$11 (35% upside, not including the dividend). This factors in ~10% increases in market share (i.e. 7% share to 7.7% share in Europe) due to a more competitive model lineup and a ~4% decreases in prices (either to undercut competitors, increase demand, etc.) across all regions.

My opinion, however, is that a model is not as applicable in this case as in others. More specifically, the industry will change dramatically in the next 5 years and modeling may fail to take this into account — the best analysis should consider both company fundamentals and management. The right C-suite is an incredibly important factor in a turnaround like Ford’s.

Ford’s executive team, including the CEO, are taking calculated steps in this overhaul. The CEO seems hesitant to unveil any “master plan” and does not consider himself a “savior” for the company — data show a “loud” turnaround almost always leads to an undesirable outcome (see researcher Jim Collins’s published studies for more info). Rather, Ford is facing the “brutal truth” by cutting its losers (sedans), revamping/improving its winners (pick ups, SUVs, and the Mustang), while keeping company financials healthy. Critics point to James Hackett’s (Ford’s CEO) lack of experience in the automotive world, but this is irrelevant — data shows great leaders possess a universal set of skills, like humility, will, and a work-horse attitude, while technical skills are learned quickly (this is why students attend liberal arts schools like Williams, by the way). Hackett admits in interviews he does not have a grand vision, but is simply comprehensively assessing Ford’s and the industry’s trends to arrive at the best decisions to drive the company forward. To be frank, Hackett could easily go on CNBC with an energized message to bring Ford “back from boring”, land on the cover of Fortune or Bloomberg Businessweek, setting its stock on a potential bullish run. As someone who owns nearly 150,000 shares of Ford stock, there is definitely a reason he has not done this already. Although the findings in this paragraph may seem highly qualitative, they are deeply rooted in data and case studies of hundreds of American corporations (see published works Good to Great and How the Mighty Fall for more information).

There is little doubt Ford is currently a “boring” company. This, however, doesn’t have to mean a “boring” investment. Ford’s turnaround is likely to be successful and, given their dividend and financial position, time is on their side. If all goes according to plan, Ford’s vehicles and technology will be almost entirely revamped by 2021, while history and data point to current leadership being a positive catalyst during the transition. Given a long term view, we can expect at least 50-55% upside over the next 4 years (via the DCF model and dividend yield). In addition, Ford’s stock can be an effective hedge against a downturn with its dividend. Maybe investing in Ford is not “chic” to bring up in a conversation with your millenial friend, but who really cares when it makes you money?

Micron: Finally A Value Stock? [Sold]

By David Shakirov


UPDATE 03/21/2019: After a rise in the stock after earnings on 03/21/2019, I recommend to unload shares at $43.50, booking a 27.5% gain. An uncertain semiconductor supply/demand dynamic and higher valuation results in a more subpar risk/reward ratio. However, the gain booked from this article is an impressive 15% above the S&P 500, for a total gain of 27.53%.


Tech stocks are no longer the loud, hard partying rock and roll band of the equity markets. Although the S&P 500 has declined 10-11% over the last three months, the technology sector is trending lower (the NASDAQ 100 is down 14% in the last 3 months). At one point a sweetheart of momentum investors, AAPL, for instance, is spurring a love-hate relationship with its shareholders with lowered transparency, demand issues, and a 30% decline in its share price. Micron (MU), however, is even more extreme.

An American chip-maker based in Idaho, Micron is in the memory-supply business, including RAM, solid state, flash drives, etc. — a key component of most electronic devices. Micron tailors memory products to customer specifications, and sells through either online or in-person sales representatives. Approximately half of its net sales stem from its ten largest customers including Oracle, GE, Google, and Cisco — major players in the cloud computing, networking, and analytics businesses. To make its memory chips, MU relies on a small number of Chinese suppliers for raw materials (including silicone, chemicals, rare-earth metals, etc.), while 88% of its orders originate outside the United States — making its business model vulnerable to tariffs, shortages, or transportation mishaps.

Since mid-2016, however, RAM prices and demand have skyrocketed, which may account for Micron’s revenue growth from $12.4B (FY2016) to $30.4B (2018).  Its stock gained strong momentum, lifting from its sub-$10 low to a high of $60 over two years as analysts cited the company as “generating increasing profits” (Benchmark) and pointed to its attractive valuation (Wells Fargo).

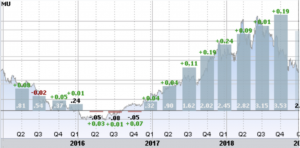
After underperformance in 2016, Micron’s Earnings Per Share have been steadily increasing for the past two years (grey bars), beating analyst expectations for 8 straight quarters (green figures). Source: E-Trade 

Since late-May, MU has declined almost 50% to $33 as analysts began to see cracks in RAM pricing and demand, an attack on Micron’s core business. Analysts focused on declining EBITDA given the weakness in its business environment. However, firms like Moody’s have reiterated that, for example, debt-to-EBITDA will continue to be sub-1 while RAM pricing is simply a cyclical (not structural) downturn.

The PHLX Semiconductor Index (SOX), a metric cited by MU’s 10-K as an accurate measure of the semiconductor market, has trailed 15% down from its peak in late May. Some of Micron’s largest competitors, including SK Hynix, have trailed down 35% (compared to Micron’s 50% drop). Given that these companies operate in the same memory-business, Micron seems to be hit hardest by the cyclical decline in prices.

Although it faces a more difficult than expected business environment, MU may now trade at an attractive valuation. Since 2016, it has paid down debt (from $12B to $11B) while doubling assets (from $22.5B to $43B) and nearly tripling revenues.  Its short term liquidity is not concerning (current ratio of 2.8x) while its debt profile is quite small (debt/equity of 0.14x). Operating income, a large focus for MU investors, has increased from $13.3B in 2014 to $15.8B in 2018. These metrics point to a strong balance sheet position and rising revenues/income. Investors are more focused on the cyclical decline in the memory-business, however, and not company fundamentals..

Given its healthy financials, the memory business landscape is a catalyst for the stock. M As competition between MU and its competitors (including Samsung and Chinese firms such as SK Hynix ) intensifies, fears of oversupply and hence memory price deflation emerge. Micron admits that the Chinese government’s direct investment into Chinese semiconductor companies poses a competitive (and possibly “unfair”) risk. Nevertheless, Micron has close to $7B of cash to spend on R&D — a significant moat for its competitive advantage, given it only spent $2.8B on research and development in 2018. Given the tough semiconductor/memory environment and tough competition, it may make sense for MU to increase its R&D expenses to protect itself even further. ? Demand, however, should grow as the development of virtual reality, cloud storage, and machine learning expand, as Micron provides a significant amount of product for these memory-reliant industries. Investors, however, seem more worried about cyclical changes in memory pricing, rather than long term sustained growth in demand.

Even if we modeled a 10% decrease in memory prices, a stagnant market share, poor worldwide RAM demand (15% total growth from 2018 to 2025), and flat margins, we would still expect a $45 price target on the stock (given a discounted cash flow analysis, performed by Trefis).. This case incorporates very conservative inputs. A more realistic case, however, incorporates declining memory prices, a continued trend of increasing market share (given rising R&D investments from its strong cash position) at slower rates to 40% in 2025 (from 35% in 2018), and 20% total growth in the DRAM market until 2025. This points to a price target of $60, or 80% upside from its $33 price.

Micron will be announcing earnings after the bell on December 18th. If it addresses the state of its business environment — the memory market — by either pointing to improvements in the market or MU’s adaptation to the price/demand pitfalls, investors may feel relieved. Rather than focusing on the short term cyclical pricing of memory, value investors should use MU as a cheap vehicle to profit from the expanding memory market. Micron’s stock price is like a loaded slingshot, pointed up. With little downside left after a 50% decline and a catalyst earnings call, it would be hard for a disappointing news to depress the stock even more. As the third largest player in a market that naturally expands with the growth of technology, in addition to a prime financial position and an oversold price (with an RSI of 40) investors should find peace in the $45-50 range within the next 6 months.